Capital-Backed Solutions for Long-Term Protection and Performance
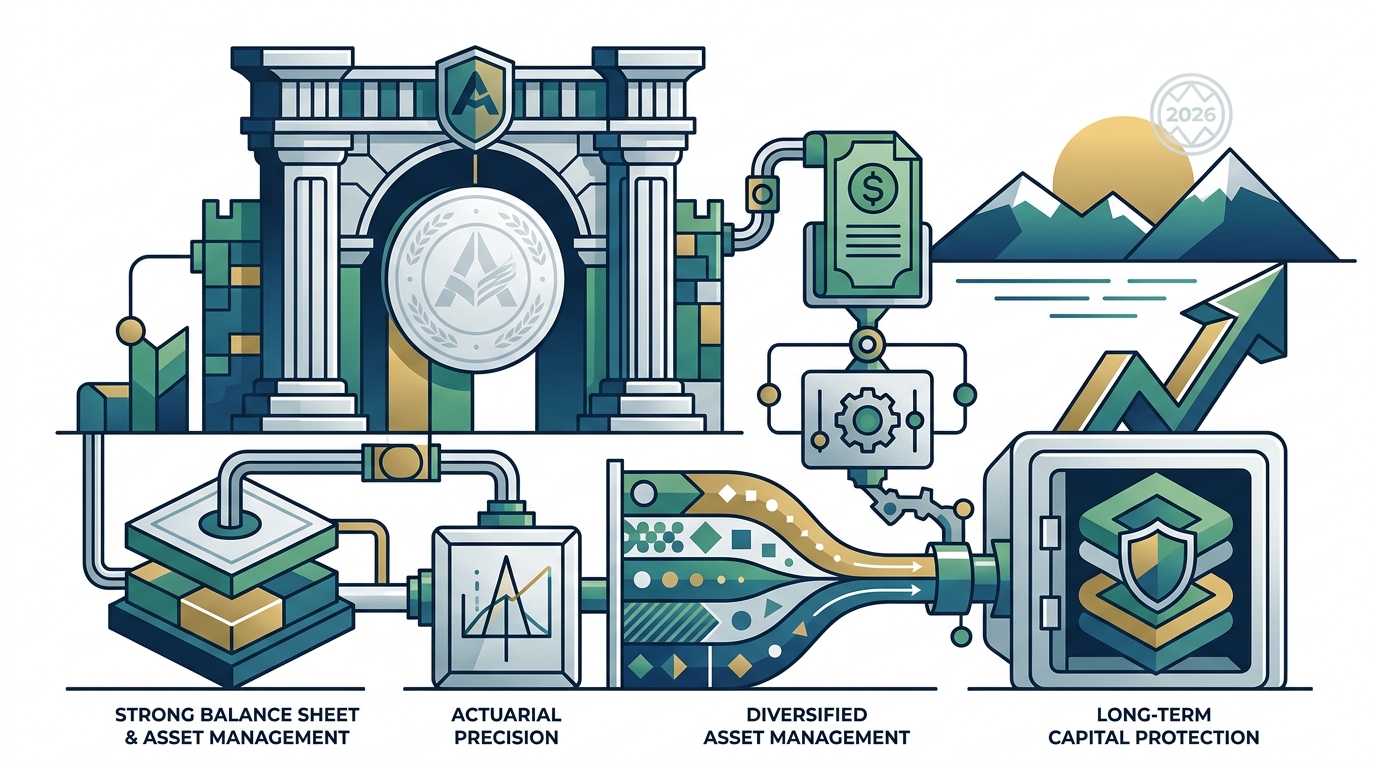
Capital-backed solutions are financial instruments where an insurer or asset manager uses its own balance sheet to guarantee returns or protect principal. For investors seeking long-term protection and performance, the best options combine regulatory oversight, actuarial precision, and diversified asset management. This guide explores how Acturion Group structures these solutions to bridge the gap between balance sheet protection and long-term performance.
Principal Protected Investments
Principal protection is a core feature of capital-backed insurance products. It ensures that the initial investment amount is preserved, often through a contractual guarantee backed by the insurer's capital. This is critical for retirees and conservative investors who cannot afford to lose their base capital.
The Role of Actuarial Precision
Actuarial precision is the mathematical and statistical discipline used to assess risk and price insurance products. At Acturion, we combine this precision with balance sheet strength to create reliable, scalable outcomes. By accurately modeling long-term liabilities, we can offer guarantees that remain solvent even during market downturns.
Retirement-Focused Structures
Retirement-focused insurance products are designed to provide income stability and long-term financial certainty. These structures often include multi-year guaranteed annuities or fixed indexed annuities. The capital backing ensures that the promised income stream is not dependent on market performance alone, but on the insurer's ability to meet its obligations.
Diversified Portfolios
Diversified portfolios are investment strategies that spread capital across various asset classes to reduce risk. In the context of capital-backed solutions, diversification is managed by professional asset managers who align long-term protection with performance. This approach helps mitigate the impact of volatility in any single asset class.
Asset Management Expertise
Asset management expertise is the professional capability to manage investments to achieve specific financial goals. Acturion integrates this expertise with its insurance platform to optimize capital usage. By managing a diversified portfolio of fixed income, equities, and alternative assets, we support sustainable growth while maintaining the capital needed to back insurance guarantees.
Capital Efficiency and Surplus
Capital efficiency is the ability to generate returns while maintaining sufficient reserves to meet regulatory and contractual obligations. We structure our solutions to enhance surplus and support balance sheet stability. This allows for more competitive product terms and greater flexibility in responding to market changes. according to Marginal efficiency of
Life Insurance
Life insurance is a contract between an insurer and a policyholder that provides a monetary benefit to designated beneficiaries upon the insured's death. In capital-backed structures, life insurance products often include investment components that offer growth potential while providing a death benefit guarantee.
Long-Duration Investment Products
Long-duration investment products are financial instruments designed to be held over many years, often decades. American Gulf, one of Acturion's licensed insurance entities, focuses on these products. They provide retirement-focused solutions with actuarial precision and capital-backed guarantees, supporting secure outcomes for individuals and institutions.
Pension Risk Transfer Programs
Pension Risk Transfer (PRT) programs are structured transfers of defined benefit obligations from a sponsor to an insurer. These programs reduce sponsor risk while preserving policyholder security. By assuming these long-term liabilities, Acturion provides a stable, capital-backed solution for pension funds seeking to manage their balance sheets effectively.
Comparison of Capital-Backed Solutions
| Solution Type | Primary Benefit | Risk Profile | Best For |
|---|---|---|---|
| Principal Protected Annuities | Guaranteed income and principal preservation | Low to Moderate | Retirees seeking stable income |
| Diversified Managed Portfolios | Growth potential with risk mitigation | Moderate | Investors seeking long-term growth |
| Life Insurance with Investment | Death benefit and potential cash value growth | Low to Moderate | Individuals planning for legacy and estate |
| Pension Risk Transfer | Liability offloading for sponsors | Low (for sponsor) | Corporate pension funds |
Key Takeaways
- Capital-backed solutions use an insurer's balance sheet to guarantee returns or protect principal.
- Actuarial precision is essential for pricing long-term liabilities and ensuring solvency.
- Diversified portfolios managed by professional asset managers help balance protection with performance.
- Life insurance products can combine death benefit guarantees with investment growth opportunities.
- Pension Risk Transfer programs allow sponsors to offload long-term liabilities to a capital-backed insurer.
- Regulatory rigor and transparency are critical for maintaining trust in capital-backed structures.
- Capital efficiency allows insurers to offer competitive terms while maintaining financial stability.
- Long-term thinking is a core value, prioritizing durability over short-term market fluctuations.
Frequently Asked Questions
What is a capital-backed solution?
A capital-backed solution is a financial product where the insurer uses its own capital to guarantee the performance or principal of the investment.
How does actuarial precision protect investors?
Actuarial precision involves using statistical models to accurately assess risk. This ensures that the insurer sets appropriate reserves and premiums to meet long-term obligations, protecting investors from insolvency risk.
What is the difference between a principal protected investment and a diversified portfolio?
A principal protected investment guarantees the return of the initial investment amount, often through an insurance contract. A diversified portfolio spreads investments across asset classes to reduce risk but does not typically guarantee principal preservation unless backed by an insurance contract.
How do Pension Risk Transfer programs work?
Pension Risk Transfer programs involve an insurer assuming the liabilities of a defined benefit pension plan. This reduces the sponsor's risk and provides a stable, capital-backed source of funding for the plan's obligations.
Why is regulatory compliance important in capital-backed solutions?
Regulatory compliance ensures that insurers maintain sufficient capital reserves and operate with transparency. This protects policyholders and investors by ensuring the insurer can meet its long-term obligations.
What role does asset management play in these solutions?
Asset management involves investing the insurer's capital in a diversified portfolio to generate returns. These returns help support the guarantees offered to policyholders and investors, enhancing the overall performance of the capital-backed solution.
Conclusion
Choosing the right capital-backed solution requires a clear understanding of your financial goals, risk tolerance, and time horizon. Acturion Group provides a unified platform that combines balance sheet strength, actuarial precision, and asset management expertise to deliver sustainable growth and protection. Whether you are seeking retirement income, life insurance, or pension risk transfer, our digital-first approach ensures transparency and efficiency. To explore how our solutions can align with your long-term strategy, for a personalized consultation.