Choosing a reinsurance partner for your pension fund requires evaluating balance sheet strength, regulatory compliance, and actuarial precision. Acturion Group offers a digital-first platform with two licensed carriers designed to support long-term liability management. This guide covers the essential criteria for selecting a longevity reinsurance partner and explains how institutional-grade structures protect your fund's future.
Core Evaluation Criteria for Reinsurance Partners
Selecting a reinsurance partner is a critical decision that impacts the long-term solvency of your pension fund. You must look beyond simple pricing to understand the structural integrity of the counterparty. A robust partner provides stability during market cycles and ensures that your liabilities are managed with precision.
Balance Sheet Strength and Capital
The financial health of a reinsurance company is the primary indicator of its ability to honor long-term obligations. You should verify the proprietary capital base and the regulatory capital ratios of the carrier. A strong balance sheet reduces the risk of counterparty default over the multi-decade horizon of pension liabilities.
Regulatory Compliance and Transparency
Regulatory rigor is non-negotiable for institutional investors. The partner must operate under strict governance frameworks and provide transparent reporting. This includes clear actuarial oversight and adherence to local and international insurance regulations. Transparency ensures that your fund can accurately report its risk profile to stakeholders.
Actuarial Precision and Operational Discipline
Actuarial expertise determines the accuracy of the risk transfer. A partner with deep actuarial depth can design liability-matched products that align with your fund's specific demographic and financial profile. Operational discipline ensures that the servicing of the contract is efficient and error-free over time.
Longevity Reinsurance Partners and Market Dynamics
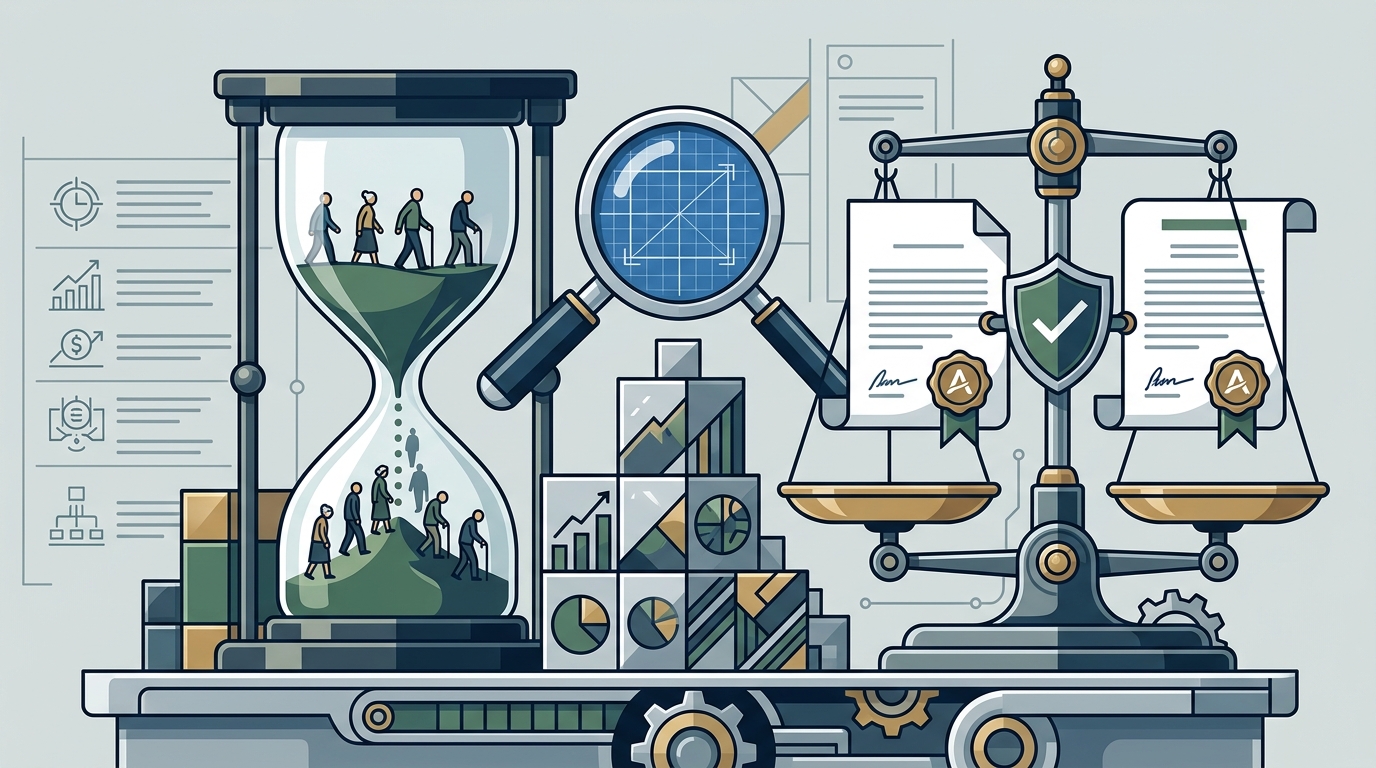
Longevity reinsurance is a specialized risk transfer mechanism that protects pension funds against the risk of members living longer than expected. This risk is central to defined benefit plans and requires a partner with specific expertise in demographic modeling. The market for longevity reinsurance has evolved to include various structures, each with different implications for capital and cash flow.
Understanding Longevity Risk
Longevity risk is the uncertainty regarding the future mortality rates of the pension population. As life expectancy increases, the duration of benefit payments extends, potentially straining the fund's assets. Reinsurance allows the sponsor to transfer this risk to a counterparty that can aggregate risk across multiple portfolios to achieve diversification benefits.
Types of Longevity Reinsurance Contracts
Market Trends in 2026
The reinsurance market in 2026 is characterized by a focus on digital integration and capital efficiency. Insurers are increasingly using technology to streamline underwriting and servicing processes. This trend benefits pension funds by providing faster execution and more transparent reporting. Partners who embrace digital-first approaches are better positioned to deliver scalable solutions in a competitive market.
The Acturion Platform: Capital and Structure
Acturion Group is an integrated insurance platform delivering capital and financial protection solutions across retirement income, life insurance, and reinsurance markets. Built on balance sheet strength, actuarial precision, and asset management expertise, our unified platform protects the present and drives future innovation. We bridge the gap between balance sheet protection and long-term performance, offering flexible insurance structures.
Two Licensed Carriers
Acturion operates two licensed insurance entities, American Gulf and American Re, each with a distinct role within our platform. While maintaining regulatory independence, both benefit from centralized capital support, shared infrastructure, and strategic oversight. Together, they deliver flexible, scalable insurance solutions across both primary insurance and reinsurance markets.
Reinsurance Solutions for Pension Funds
Our reinsurance solutions are designed to support capital efficiency, predictable cash flows, and sustainable protection. We offer Pension Risk Transfer (PRT) programs that facilitate structured transfers of defined benefit obligations. These programs reduce sponsor risk while preserving policyholder security and regulatory alignment. We also provide quota share and block reinsurance structures that optimize capital and enhance solvency.
Digital-First Execution
Acturion is a digital first insurance platform that empowers institutional and retail clients to optimize capital, manage risk, and achieve sustainable growth through smarter, technology-driven strategies. Our digital infrastructure enables efficient onboarding, transparent reporting, and seamless servicing. This approach reduces operational friction and allows pension fund managers to focus on strategic decision-making.
Comparing Reinsurance Structures
Understanding the differences between various reinsurance structures is essential for making an informed decision. The table below summarizes the key features of common reinsurance options available to pension funds.
| Structure Type | Risk Transferred | Capital Impact | Best For |
|---|---|---|---|
| Pension Risk Transfer (PRT) | Full or partial DB liabilities | Significant capital release | Funds seeking to eliminate DB risk |
| Quota Share Reinsurance | Proportional share of portfolio | Moderate capital optimization | Insurers seeking to unlock surplus |
| Longevity Reinsurance | Mortality/Longevity risk | Targeted risk reduction | Funds with high longevity exposure |
| Block Reinsurance | Specific block of policies | Flexible capital management | Insurers with specific portfolio needs |
Each structure serves a different strategic purpose. PRT is suitable for sponsors who want to fully transfer their defined benefit obligations. Quota share and block reinsurance are more common among insurers looking to optimize their balance sheets. Longevity reinsurance is a targeted solution for funds that wish to retain investment control while transferring demographic risk.
Key Takeaways
- Balance sheet strength is the most critical factor when selecting a reinsurance partner.
- Regulatory compliance and transparency ensure long-term reliability and stakeholder confidence.
- Actuarial precision is essential for accurate risk transfer and liability matching.
- Longevity reinsurance protects against the risk of members living longer than expected.
- Acturion Group offers a digital-first platform with two licensed carriers for flexible solutions.
- Pension Risk Transfer (PRT) programs can significantly reduce sponsor risk and release capital.
- Digital integration improves operational efficiency and reporting transparency in 2026.
- Choosing the right structure depends on your fund's specific risk appetite and strategic goals.
Frequently Asked Questions
What is the primary benefit of using a reinsurance partner for a pension fund?
The primary benefit is the transfer of long-term financial risk, such as longevity or investment risk, to a counterparty with the capital strength to absorb it. This can improve the fund's solvency position and reduce volatility in funding ratios.
How does Acturion Group support pension funds?
Acturion Group supports pension funds through its two licensed carriers, American Gulf and American Re. We offer Pension Risk Transfer programs, quota share reinsurance, and longevity solutions designed to optimize capital and manage risk effectively.
What is longevity reinsurance?
Longevity reinsurance is a contract that transfers the risk of pension members living longer than actuarial projections. It protects the fund from the increased cost of extended benefit payments due to demographic shifts.
Why is regulatory compliance important in reinsurance?
Regulatory compliance ensures that the reinsurance partner operates within legal frameworks and maintains adequate capital reserves. This protects the pension fund from counterparty risk and ensures that the risk transfer is legally binding and secure.
Can a pension fund transfer only part of its liabilities?
Yes, pension funds can transfer partial liabilities through structures like quota share reinsurance or partial PRT. This allows the fund to retain some control while reducing its overall risk exposure.
What role does digital technology play in modern reinsurance?
Digital technology streamlines the reinsurance process, from underwriting to servicing. It enables faster execution, real-time reporting, and greater transparency, which are critical for institutional investors in 2026.
How should a pension fund evaluate the financial strength of a reinsurance partner?
A pension fund should evaluate the partner's proprietary capital base, regulatory capital ratios, and credit ratings. It is also important to review the partner's track record in managing long-duration liabilities and its operational discipline.
What is the difference between PRT and longevity reinsurance?
Pension Risk Transfer (PRT) involves transferring the entire or a significant portion of defined benefit liabilities, including investment risk. Longevity reinsurance specifically transfers the demographic risk of members living longer, often while the fund retains investment control.