
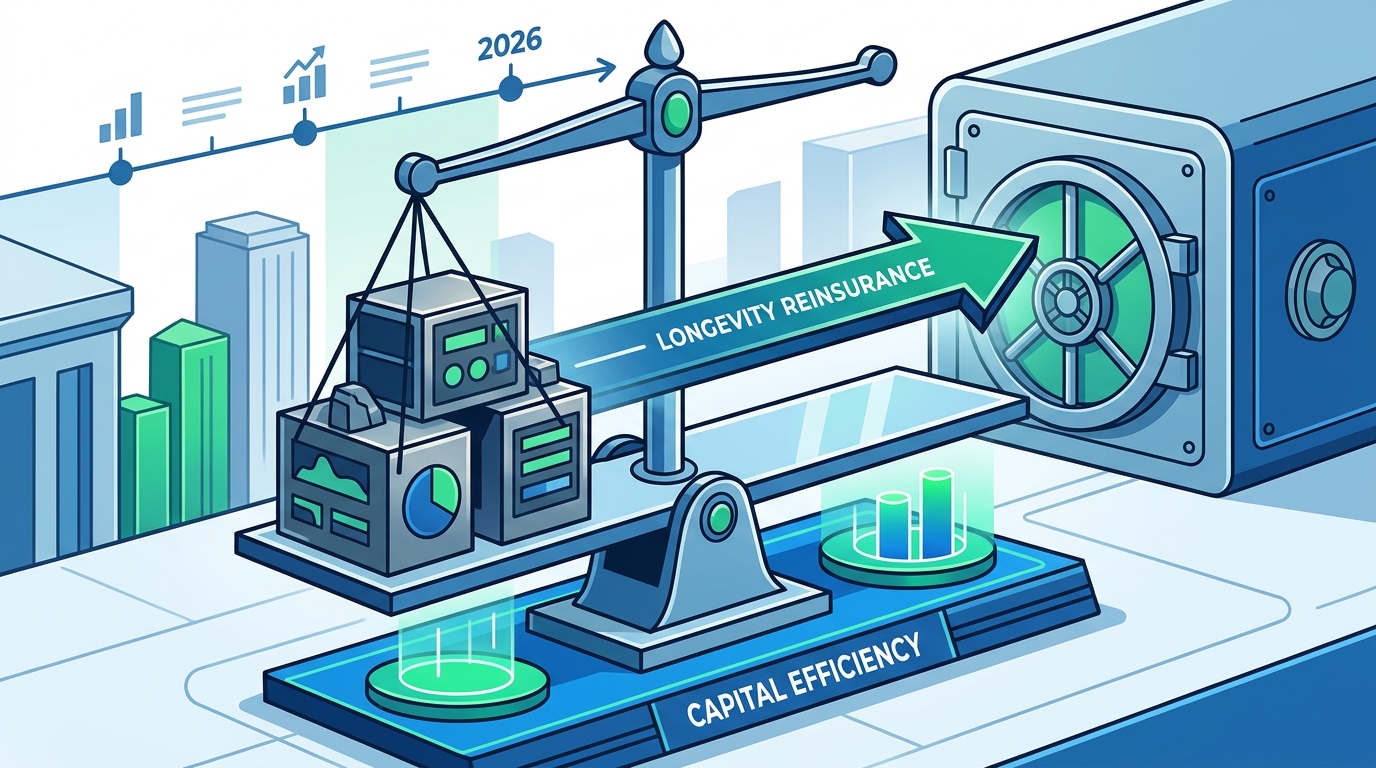
Longevity reinsurance is a risk transfer mechanism where insurers cede the risk of policyholders living longer than expected to a reinsurer. In the current market, this tool is essential for managing balance sheet volatility and ensuring the sustainability of retirement income products. By offloading this specific liability, primary insurers can maintain capital efficiency while offering secure, long-duration guarantees to their clients. according to Potential Money Laundering
Market Dynamics and Capital Efficiency
The annuity market has evolved significantly, with a growing emphasis on capital optimization. Insurers face the challenge of holding substantial reserves to cover potential longevity risk, which can tie up capital that could otherwise be deployed for growth. Longevity reinsurance allows carriers to release this trapped surplus. This release of capital improves the insurer's solvency ratios and enhances their ability to issue new business without eroding their financial strength. For additional details, review the About Us Acturion.
Structural Options for Risk Transfer
There are several ways to structure longevity reinsurance agreements, each with distinct implications for risk and reward. The most common structures include quota share, block reinsurance, and pension risk transfer programs. Quota share agreements involve the reinsurer taking a fixed percentage of the premiums and claims, providing a straightforward method for spreading risk. Block reinsurance, on the other hand, allows for more tailored solutions where specific portfolios or risk layers are transferred. For additional details, review the Terms of Service Acturion.
Pension risk transfer programs represent a specialized form of longevity reinsurance, where sponsors of defined benefit plans transfer their obligations to an insurance carrier. This transfer reduces the sponsor's balance sheet risk and provides retirees with a secure, guaranteed income stream. The choice of structure depends on the specific needs of the primary insurer, including their capital position, risk appetite, and strategic goals. A well-designed structure aligns the interests of both parties, ensuring a durable and mutually beneficial partnership.
Regulatory Impact and Solvency
Transparency and regulatory rigor are paramount in these transactions. Insurers must provide clear governance, actuarial oversight, and transparent reporting to regulators and stakeholders. This ensures that the reinsurance agreements are sound and that the risks are properly managed. The regulatory environment continues to evolve, with a focus on ensuring the long-term stability of the insurance industry. Adhering to these standards builds trust and confidence in the reinsurance market.
Benefits for Institutional Partners
Institutional partners, such as pension funds and insurance companies, benefit from longevity reinsurance in several ways. For pension sponsors, transferring longevity risk can improve their financial health and reduce the volatility of their balance sheets. This can lead to better credit ratings and lower borrowing costs. For insurance companies, reinsurance provides a means to manage their risk exposure and enhance their capital efficiency. This allows them to focus on their core competencies, such as product development and customer service.
The partnership between primary insurers and reinsurers is built on trust and long-term thinking. Both parties must have a clear understanding of the risks involved and the benefits of the transfer. This alignment of interests ensures that the reinsurance agreement is sustainable and adds value to both organizations. The digital integration of insurance platforms further enhances these partnerships by enabling efficient data sharing and risk assessment.
Key Takeaways
- Longevity reinsurance is a critical tool for managing the risk of policyholders living longer than expected.
- It allows insurers to release trapped capital, improving solvency ratios and supporting new business issuance.
- Common structures include quota share, block reinsurance, and pension risk transfer programs.
- Regulatory frameworks require adequate capital and transparency, which reinsurance helps to address.
- Institutional partners benefit from reduced balance sheet risk and improved financial stability.
- Successful reinsurance partnerships are built on trust, long-term thinking, and digital integration.
Frequently Asked Questions
What is longevity reinsurance?
Longevity reinsurance is a contract where an insurer transfers the risk of policyholders living longer than projected to a reinsurer.
How does longevity reinsurance benefit insurers?
It reduces the capital requirements for the primary insurer by transferring the longevity risk, thereby improving capital efficiency and solvency.
What are the common structures of longevity reinsurance?
Common structures include quota share, block reinsurance, and pension risk transfer programs, each offering different levels of risk transfer.
How does regulatory oversight affect longevity reinsurance?
Regulators require insurers to maintain adequate capital and provide transparent reporting, which reinsurance helps to achieve by reducing the insurer's risk exposure. according to Who Pays for
Who are the typical participants in longevity reinsurance?
The typical participants are primary life insurance companies and pension sponsors, who transfer their longevity risk to specialized reinsurance carriers.
Does longevity reinsurance impact the policyholder?
Generally, the policyholder's benefits remain unchanged, but the security of those benefits is enhanced by the involvement of a well-capitalized reinsurer.
How does digital integration play a role in longevity reinsurance?
Digital platforms facilitate efficient data sharing, risk assessment, and administration of reinsurance agreements, improving the overall process.How can I learn more about Acturion's reinsurance solutions?
You can explore the details of our reinsurance offerings by visiting our insurance solutions page.
Explore Acturion's Reinsurance Expertise
Acturion Group is an integrated insurance platform delivering capital and financial protection solutions across retirement income, life insurance, and reinsurance markets. Our reinsurance carrier, American Re, provides tailored risk transfer solutions for insurers and pension funds. We support balance sheet efficiency, long-term liability management, and structural flexibility across global insurance markets. To discuss how our longevity reinsurance solutions can support your strategic goals, today.
according to Potential Money Laundering