
Annuity Buyouts Explained: Securing Retirement Income
An annuity buyout is a financial transaction where an insurance company assumes the obligation to pay future retirement benefits in exchange for a lump sum or structured payment. This mechanism transfers longevity and market risk from the original sponsor to the insurer. For individuals and institutions, this process provides immediate certainty and eliminates the uncertainty of managing long-term liabilities. Acturion Group specializes in these capital-backed solutions, ensuring that retirement income streams remain stable and predictable regardless of market cycles. according to Strategies for Using
The Mechanics of an Annuity Buyout
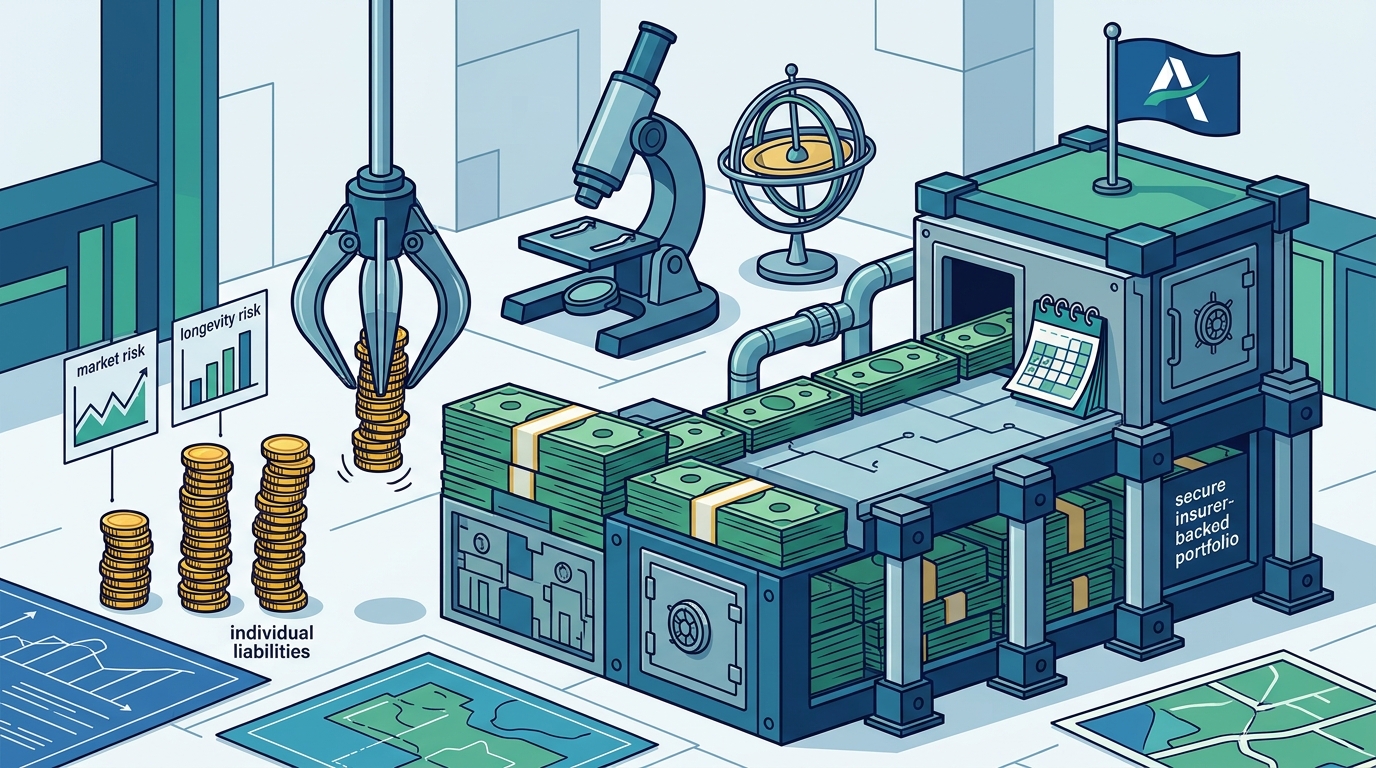
Understanding the mechanics requires looking at the flow of capital and liability. An annuity buyout is a risk transfer tool that allows a pension sponsor or individual to offload future payment obligations. The process begins with a valuation of the remaining liabilities. The insurer calculates the present value of all future payments, factoring in mortality tables, interest rates, and inflation projections. Once the valuation is complete, the insurer issues a bid. If the sponsor accepts, the liability moves to the insurer's balance sheet. This is not a loan; it is a permanent transfer of responsibility. The sponsor receives capital, and the insurer assumes the duty to pay the annuitant for life.
Valuation and Pricing
Pricing is the most critical phase of the transaction. Insurers use actuarial models to determine the cost of the buyout. These models rely on historical data and current market conditions. A higher interest rate environment typically lowers the cost of the buyout because the insurer can invest the premium at higher yields. Conversely, low rates increase the cost. The precision of this valuation ensures that the insurer remains solvent while the sponsor receives a fair market value for the liability.
Buyouts for Individual Retirees
For individual retirees, the concept of a buyout often manifests as purchasing a single-premium immediate annuity (SPIA). This is a direct exchange of a lump sum for a guaranteed income stream. The individual pays the insurance company a one-time fee. In return, the company guarantees monthly payments for the rest of the individual's life. This structure protects against the risk of outliving one's savings. It is a definitive solution for those who have accumulated significant assets but lack a steady income source. The guarantee is backed by the insurer's financial strength and regulatory reserves.
Principal Protection
Institutional Pension Risk Transfer
In the corporate sector, annuity buyouts are known as Pension Risk Transfer (PRT) programs. These are large-scale transactions where a company transfers its defined benefit pension obligations to an insurance carrier. The company pays a lump sum to the insurer. The insurer then takes over the responsibility of paying the retirees. This allows the company to remove the pension liability from its balance sheet. It improves financial ratios and frees up capital for core business operations. The insurer, in turn, gains a long-term asset that matches its long-duration liabilities.
Regulatory and Financial Benefits
For institutions, the benefits extend beyond simple balance sheet cleanup. Removing pension liabilities reduces volatility in earnings. It also lowers the risk of funding shortfalls during market downturns. The insurer assumes the investment risk, which is a significant burden for many corporate sponsors. This transfer allows the company to focus on its primary business rather than managing a complex pension portfolio. It is a strategic move that enhances long-term financial stability. according to Publication 575 2025
Risk Transfer and Longevity
The core value of an annuity buyout lies in risk transfer. The primary risk being transferred is longevity risk. This is the risk that an individual or a group of retirees will live longer than expected. If retirees live longer, the sponsor must pay for more years than anticipated. This can deplete reserves and cause financial distress. By transferring this risk to an insurer, the sponsor eliminates the uncertainty. The insurer is designed to manage this risk across a large pool of clients. This pooling effect allows the insurer to predict outcomes with greater accuracy. The result is a stable, predictable income stream for the retiree.
Market Risk Mitigation
Market risk is another critical factor. Pension funds and individual savings are exposed to stock and bond market fluctuations. A buyout removes this exposure. The insurer manages the investments, but the payment obligation is fixed. The retiree receives the same amount regardless of market performance. This decoupling of income from market volatility is a key benefit. It provides peace of mind during economic downturns. The retiree knows their income will not drop if the stock market crashes. according to Publication 575 2025
Acturion's Approach to Annuity Solutions
Acturion Group operates as a digital-first insurance platform that delivers capital and income solutions. The company combines balance sheet strength with actuarial precision. This approach ensures that the annuity products offered are robust and reliable. Acturion serves both retail customers and institutional clients. The company's two licensed insurance carriers, American Gulf and American Re, play distinct roles. American Gulf focuses on long-duration investment products for individuals. American Re provides reinsurance solutions for other insurers. This dual structure allows Acturion to offer comprehensive coverage across the retirement landscape.
Capital-Backed Guarantees
The guarantees provided by Acturion are backed by significant proprietary capital. This capital base provides a buffer against unexpected losses. It ensures that the company can meet its obligations even in adverse scenarios. The use of digital integration streamlines the process for clients. It reduces administrative burden and improves transparency. Clients can access their information and manage their policies through digital platforms. This efficiency is a hallmark of Acturion's modern approach to insurance. It aligns with the needs of today's tech-savvy retirees and institutions.
Key Takeaways
- An annuity buyout is a permanent transfer of future payment obligations to an insurance company.
- For individuals, it converts a lump sum into a guaranteed lifetime income stream.
- Institutional buyouts, or PRT, allow companies to remove pension liabilities from their balance sheets.
- The primary risks transferred are longevity risk and market volatility.
- Valuation relies on actuarial models that factor in mortality, interest rates, and inflation.
- Acturion Group provides capital-backed solutions through its licensed carriers, American Gulf and American Re.
- Digital integration enhances transparency and efficiency for clients managing their retirement income.
Frequently Asked Questions
What is the main benefit of an annuity buyout for a retiree?
The main benefit is the elimination of longevity risk. It guarantees a steady income for life, ensuring that the retiree does not outlive their savings.
How does an institutional annuity buyout differ from an individual one?
Institutional buyouts involve large-scale transfers of pension liabilities to improve balance sheet health. Individual buyouts focus on converting personal assets into guaranteed income.
Who assumes the investment risk in a buyout?
The insurance company assumes the investment risk. The sponsor or individual no longer bears the burden of managing the assets that fund the payments.
Can an annuity buyout be reversed?
Generally, no. Once the liability is transferred, it is a permanent transaction. The insurer takes full responsibility for the payments.
What role does capital strength play in an annuity buyout?
Capital strength ensures the insurer can meet its long-term obligations. A strong balance sheet provides security for the annuitant and the sponsor.
How does Acturion support these transactions?
Acturion provides the infrastructure, licensing, and actuarial expertise to execute these transactions. Its digital platform streamlines the process for clients.
Conclusion
An annuity buyout is a powerful tool for securing retirement income. It transfers critical risks to a specialized insurer, providing certainty and stability. Whether for an individual seeking lifetime income or a corporation managing pension liabilities, the benefits are clear. It removes the uncertainty of the future and replaces it with a guaranteed outcome. Acturion Group offers the expertise and capital strength to support these transactions. To explore how these solutions can fit your financial strategy, today.