How Financial Reinsurance Structures Optimize Life Insurer Capital
Financial reinsurance structures allow life insurers to transfer specific liabilities to a reinsurer in exchange for a premium, directly reducing the capital required to support those obligations. By offloading long-duration risks, primary carriers can free up trapped surplus, improve solvency ratios, and deploy capital into higher-yielding assets. This mechanism is critical for maintaining balance sheet stability while supporting growth initiatives.
Capital Efficiency and Surplus Release
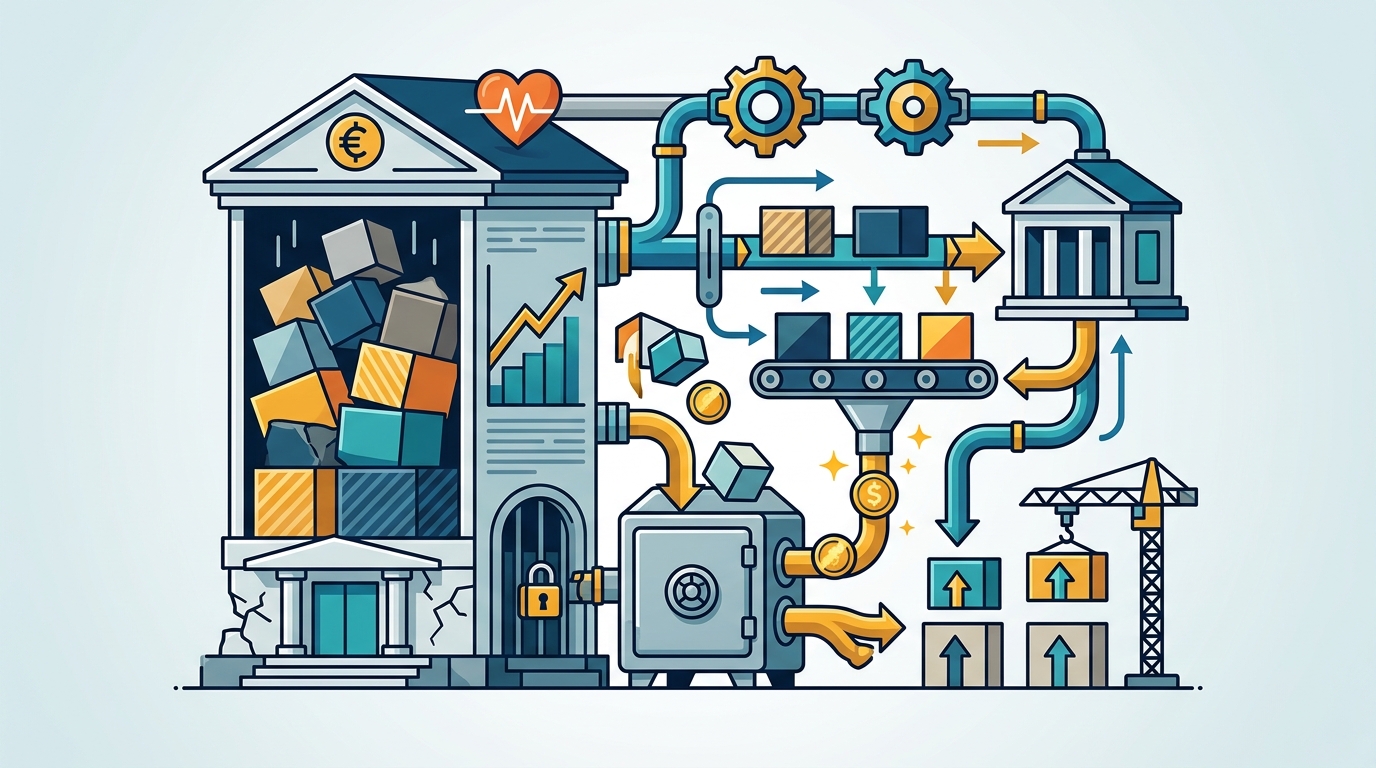
Capital efficiency is the primary driver for life insurers seeking to optimize their balance sheets. When a primary insurer holds a large block of long-duration liabilities, it must maintain a significant amount of capital to meet regulatory solvency requirements. This capital often sits idle, earning returns that do not match the risk profile of the underlying assets. Financial reinsurance structures address this inefficiency by transferring the liability to a counterparty with a stronger capital base or a different risk appetite. For additional details, review the Contact Us Acturion.
Quota Share and Block Reinsurance
Quota share reinsurance is a structure where the reinsurer assumes a fixed percentage of the premiums and claims associated with a specific block of business. This arrangement is particularly effective for in-force portfolios where the primary insurer wants to reduce exposure without terminating the policyholder relationship. The reinsurer typically pays a ceding commission, which offsets the cost of the reinsurance premium and helps maintain the insurer's profitability. For additional details, review the Home Acturion.
Block reinsurance, on the other hand, involves the transfer of an entire portfolio of policies. This is often used in mergers and acquisitions or when an insurer is exiting a specific product line. The key benefit of block reinsurance is the complete removal of the associated capital requirements. For instance, a life insurer might transfer a block of term life policies to a reinsurer, thereby eliminating the need to hold capital against the mortality risk of that specific group. This allows the primary carrier to focus its resources on core competencies and new product development.
Pension Risk Transfer Programs
Pension Risk Transfer (PRT) programs are a specialized form of financial reinsurance designed for defined benefit pension plans. These programs allow plan sponsors to transfer the obligation to pay future benefits to an insurance company. The insurer assumes the risk of longevity, investment performance, and interest rate fluctuations. In exchange, the sponsor pays a lump sum or a series of payments to the insurer.
Regulatory Impact and Solvency
Regulatory frameworks play a crucial role in determining the capital impact of reinsurance transactions. In the United States, the Risk-Based Capital (RBC) framework requires insurers to hold capital based on the risks they assume. Reinsurance can reduce RBC charges if the reinsurer is approved by the regulator. However, the extent of the capital relief depends on the creditworthiness of the reinsurer and the structure of the agreement.
The implication of regulatory approval is that insurers can achieve significant capital relief without compromising their solvency position. For example, a carrier that cedes 50% of its long-term care liabilities to a highly rated reinsurer may see a proportional reduction in its RBC charges. This allows the carrier to maintain a strong solvency ratio while supporting growth. Regulatory rigor and transparency are essential in these transactions, ensuring that the capital relief is justified by the actual risk transfer.
Implementation and Strategic Alignment
Implementing financial reinsurance structures requires careful strategic planning. Insurers must evaluate their capital needs, risk appetite, and growth objectives before entering into a reinsurance agreement. The choice of structure, whether quota share, block, or PRT, depends on the specific goals of the transaction. For example, an insurer seeking to exit a product line might choose block reinsurance, while one seeking to optimize capital for growth might choose quota share.
Strategic alignment is also critical. The reinsurance transaction should support the insurer's long-term business plan. This includes considering the impact on distribution partners, policyholders, and regulatory stakeholders. A well-structured reinsurance agreement can enhance the insurer's reputation for stability and reliability. For instance, a carrier that uses reinsurance to support its retirement income products can demonstrate its commitment to long-term security, thereby attracting more customers and distribution partners.
Key Takeaways
- Financial reinsurance structures allow life insurers to transfer liabilities, reducing the capital required to support those obligations.
- Quota share reinsurance is effective for reducing exposure to in-force portfolios while maintaining policyholder relationships.
- Block reinsurance enables the complete removal of specific portfolios, freeing up trapped surplus for redeployment.
- Pension Risk Transfer programs help plan sponsors eliminate volatile pension liabilities from their balance sheets.
- Regulatory approval is essential for achieving capital relief under frameworks like Risk-Based Capital.
- Strategic alignment ensures that reinsurance transactions support the insurer's long-term business objectives.
- Transparency and regulatory rigor are critical in maintaining the integrity of reinsurance transactions.
Frequently Asked Questions
What is the primary benefit of financial reinsurance for life insurers?
The primary benefit is the optimization of capital usage, allowing insurers to free up trapped surplus and improve solvency ratios.
How does quota share reinsurance differ from block reinsurance?
Quota share reinsurance involves ceding a percentage of premiums and claims, while block reinsurance involves transferring an entire portfolio of policies.
What is a Pension Risk Transfer (PRT) program?
A PRT program is a reinsurance structure that allows plan sponsors to transfer the obligation to pay future pension benefits to an insurance company.
How does regulatory approval affect capital relief?
Regulatory approval ensures that the reinsurer is creditworthy, allowing the primary insurer to achieve capital relief under frameworks like Risk-Based Capital.
Can reinsurance structures support growth initiatives?
Yes, by freeing up capital, insurers can deploy resources into new business, acquisitions, or higher-yielding investments.
What role does transparency play in reinsurance transactions?
Transparency ensures that the capital relief is justified by the actual risk transfer, maintaining the integrity of the transaction and regulatory compliance.
How do reinsurance structures impact policyholders?
Reinsurance structures can enhance the stability and reliability of the insurer, providing greater security for policyholders.