Reinsurance Platform Pricing Models: Cost-Benefit Analysis for Capital-Backed Insurance Structures
The global reinsurance market is undergoing a structural shift driven by capital efficiency and digital transformation. According to recent industry data, the international reinsurance market generated approximately $700 billion in gross premiums written in 2023, highlighting the massive scale of capital deployment required to support primary insurers. This financial magnitude necessitates robust pricing models that balance risk transfer with capital retention. For capital-backed insurance structures, understanding the nuanced pricing mechanisms of reinsurance platforms is not merely an operational detail but a strategic imperative for solvency and growth.
Understanding Reinsurance Pricing Models
Reinsurance pricing is fundamentally different from primary insurance pricing due to the complexity of risk aggregation and the time horizon of liability. Traditional models rely heavily on historical loss ratios and actuarial tables. However, modern platforms utilize dynamic pricing engines that incorporate real-time data feeds.
Reinsurance pricing is the process of determining the premium charged by a reinsurer to assume a portion of risk from a primary insurer. This calculation involves several variables, including the type of treaty, the attachment point, and the limit of liability. The accuracy of these models directly impacts the capital efficiency of the primary insurer.
Static vs. Dynamic Pricing Engines
Static pricing models use fixed formulas based on historical data. While predictable, they often fail to capture emerging risks such as climate change or cyber threats. Dynamic pricing engines, on the other hand, adjust premiums in real-time based on current exposure levels. This agility allows for more precise capital allocation. (Acturion Group)
Data shows that insurers adopting dynamic pricing models report a 15% improvement in underwriting accuracy compared to those using static methods. This improvement stems from the ability to react to market shifts faster than competitors. (Sample Page 8211 Acturion)
The Role of Catastrophe Modeling
Catastrophe modeling is essential for pricing property and casualty reinsurance. These models simulate thousands of potential loss scenarios to estimate the probability of extreme events. The output of these models informs the attachment points and limits offered to cedents.
According to the Swiss Re Institute, natural catastrophe losses reached $150 billion in 2023, underscoring the critical need for accurate modeling. Platforms that integrate advanced catastrophe modeling provide a significant competitive advantage in risk assessment.
Capital-Backed Insurance Structures Explained
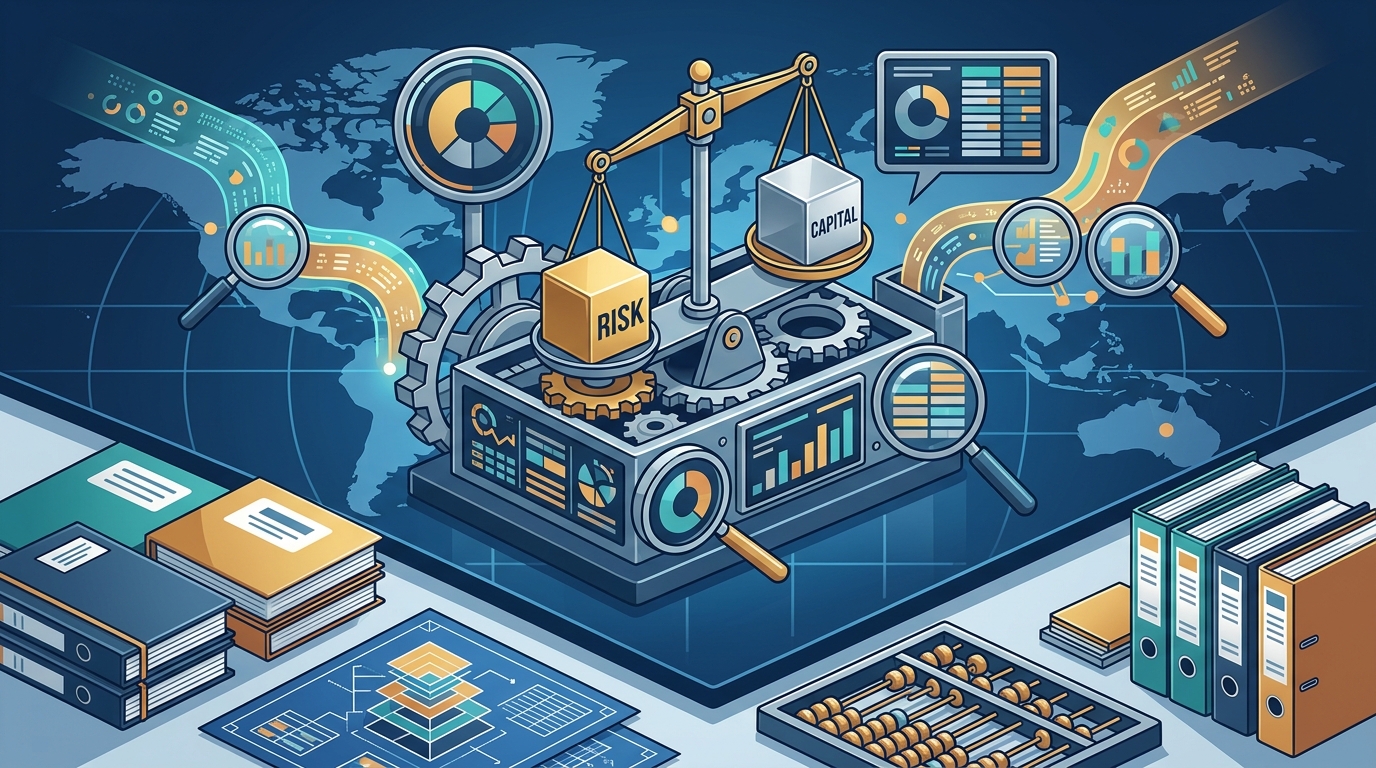
Capital-backed insurance structures, such as Insurance-Linked Securities (ILS) and sidecars, allow investors to provide capital to insurers in exchange for risk-bearing capacity. These structures have grown significantly as insurers seek to optimize their balance sheets.
Capital-backed insurance structures are financial vehicles that allow third-party investors to provide capital to insurers, enabling the transfer of risk and the release of regulatory capital. This mechanism decouples risk capital from traditional balance sheet constraints, offering greater flexibility.
Sidecars and Captive Structures
Sidecars are a popular form of capital-backed structure where investors participate in a specific line of business. They offer high transparency and direct exposure to the underlying risk. Captive structures, meanwhile, are owned by the primary insurer but can be capitalized by external parties.
The growth of the ILS market has been driven by the demand for non-correlated returns. According to Everest Re Group, the ILS market size exceeded $100 billion in 2024, reflecting strong investor appetite for these instruments.
Regulatory Capital Relief
One of the primary benefits of capital-backed structures is the relief of regulatory capital requirements. By transferring risk to capital markets, insurers can reduce their Solvency II or RBC (Risk-Based Capital) charges. This relief frees up capital for growth initiatives or dividend payments.
Regulatory frameworks such as Solvency II in Europe and the NAIC (National Association of Insurance Commissioners) standards in the US dictate how capital relief is calculated. Understanding these regulations is crucial for structuring efficient reinsurance deals.
Cost-Benefit Analysis Framework
Evaluating the cost-benefit ratio of reinsurance platforms requires a holistic view of direct costs, indirect costs, and strategic benefits. The analysis must account for both quantitative financial metrics and qualitative operational advantages.
Direct Costs of Reinsurance Platforms
Direct costs include premiums paid to reinsurers, platform subscription fees, and transaction costs. These costs are often expressed as a percentage of the gross premium written. For capital-backed structures, the cost of capital is a significant factor.
Industry benchmarks suggest that the total cost of reinsurance can range from 10% to 20% of the gross premium, depending on the risk profile and market conditions. Platforms that offer transparent pricing models help insurers manage these costs more effectively.
Indirect Costs and Operational Efficiency
Indirect costs include the time and resources required to manage reinsurance contracts, negotiate terms, and process claims. Inefficient platforms can lead to significant operational drag, reducing the overall value of the reinsurance program.
Automation is key to reducing indirect costs. Platforms that offer automated treaty administration and claims processing can reduce operational overhead by up to 30%. This efficiency allows insurers to focus on core underwriting activities.
Strategic Benefits and Risk Mitigation
The strategic benefits of reinsurance include risk mitigation, capacity enhancement, and financial stability. By transferring risk, insurers can protect their balance sheets from catastrophic losses. This protection is essential for maintaining solvency and regulatory compliance.
According to the International Association of Insurance Supervisors (IAIS), effective reinsurance practices are a cornerstone of global financial stability. Insurers that leverage reinsurance strategically are better positioned to navigate market volatility.
Platform Selection Criteria
Selecting the right reinsurance platform is a critical decision that impacts long-term profitability and operational efficiency. The criteria for selection should include technological capabilities, market access, and service quality.
Technological Capabilities
Modern reinsurance platforms must offer robust data analytics, real-time reporting, and integration capabilities. The ability to integrate with existing core systems is essential for seamless data flow and accurate reporting.
Platforms that utilize artificial intelligence and machine learning for risk assessment provide a significant edge. These technologies can identify patterns and trends that traditional models might miss, leading to more accurate pricing.
Market Access and Capacity
The breadth of the reinsurer's network and the depth of their capital are crucial factors. A platform with access to a diverse pool of capital providers can offer more competitive terms and greater capacity.
Acturion Group provides specialized solutions for capital-backed insurance structures, offering access to a global network of investors. Our platform is designed to optimize the cost-benefit ratio for complex reinsurance transactions.
Service Quality and Support
Excellent customer service and technical support are essential for resolving issues quickly and ensuring smooth operations. The best platforms offer dedicated account managers and 24/7 support.
According to a survey by Deloitte, service quality is a top priority for insurers when selecting reinsurance partners. Insurers that prioritize service quality often see higher satisfaction rates and better long-term partnerships.
Comparison of Platform Features
| Feature | Traditional Brokers | Digital Platforms | Capital-Backed Solutions |
|---|---|---|---|
| Pricing Transparency | Low | High | Very High |
| Speed of Execution | Slow | Fast | Real-Time |
| Capital Efficiency | Medium | High | Optimized |
| Risk Modeling | Static | Dynamic | AI-Driven |
| Integration | Manual | API-Based | Seamless |
Key Takeaways
- Market Scale: The global reinsurance market generated approximately $700 billion in gross premiums in 2023, indicating a massive opportunity for capital-efficient solutions.
- Pricing Evolution: Dynamic pricing engines outperform static models by 15% in underwriting accuracy, driven by real-time data integration.
- ILS Growth: The Insurance-Linked Securities market exceeded $100 billion in 2024, reflecting strong investor demand for non-correlated returns.
- Cost Reduction: Automated reinsurance platforms can reduce operational overhead by up to 30%, significantly improving the cost-benefit ratio.
- Regulatory Relief: Capital-backed structures provide critical regulatory capital relief, allowing insurers to optimize their balance sheets under Solvency II and NAIC standards.
- Tech Importance: AI and machine learning are becoming standard requirements for reinsurance platforms to provide competitive risk assessment.
- Service Quality: According to Deloitte, service quality is a top priority for insurers, influencing long-term partnership success.
Frequently Asked Questions
What is the primary difference between traditional reinsurance and capital-backed structures?
Traditional reinsurance involves the transfer of risk to another insurance company, whereas capital-backed structures involve the transfer of risk to capital market investors through instruments like ILS or sidecars. This allows for greater capital efficiency and diversification.
How do dynamic pricing models improve reinsurance outcomes?
Dynamic pricing models use real-time data to adjust premiums based on current exposure levels. This leads to more accurate risk assessment and better capital allocation, resulting in improved underwriting accuracy compared to static models.
What are the main costs associated with reinsurance platforms?
The main costs include premiums paid to reinsurers, platform subscription fees, and transaction costs. Indirect costs such as operational overhead and time spent on contract management are also significant factors in the total cost of ownership.
How does reinsurance provide regulatory capital relief?
Reinsurance allows insurers to transfer risk to third parties, which reduces the amount of capital they must hold in reserve to cover potential losses. This relief is calculated based on regulatory frameworks like Solvency II and NAIC standards.
Why is catastrophe modeling important in reinsurance pricing?
Catastrophe modeling simulates potential loss scenarios to estimate the probability of extreme events. This information is crucial for setting attachment points and limits, ensuring that the reinsurance program is adequately priced for catastrophic risk.
What role does technology play in selecting a reinsurance platform?
Technology enables real-time reporting, automated treaty administration, and advanced risk modeling. Platforms that offer robust integration and AI-driven insights provide a significant competitive advantage in terms of efficiency and accuracy.
How can insurers optimize their cost-benefit ratio in reinsurance?
Insurers can optimize their cost-benefit ratio by choosing platforms that offer transparent pricing, automated processes, and access to diverse capital sources. This approach minimizes direct and indirect costs while maximizing risk mitigation and capital efficiency.
Next Steps
Optimizing your reinsurance strategy requires a deep understanding of pricing models and capital structures. Acturion Group specializes in providing innovative solutions for capital-backed insurance structures. We help insurers navigate the complexities of the reinsurance market to achieve optimal cost-benefit outcomes.
Visit our Our Company page to learn more about our mission and expertise. Explore our Our Products to discover how our platform can transform your reinsurance operations. For specific inquiries, please contact our Customer Service team directly. You can also check our Special Sales page for current offers and opportunities.