The global annuity market has experienced a structural shift toward consolidation, driven by the need for operational efficiency and capital optimization. According to recent industry analyses, consolidated issuance models can reduce administrative overhead by up to 30% compared to fragmented legacy systems. This reduction in friction allows insurers to offer more competitive pricing structures to policyholders while maintaining robust solvency margins. The integration of reinsurance partnerships further amplifies these benefits by transferring specific longevity and mortality risks, thereby stabilizing the cost of capital required to support long-term liabilities.
Understanding Consolidated Annuity Issuance
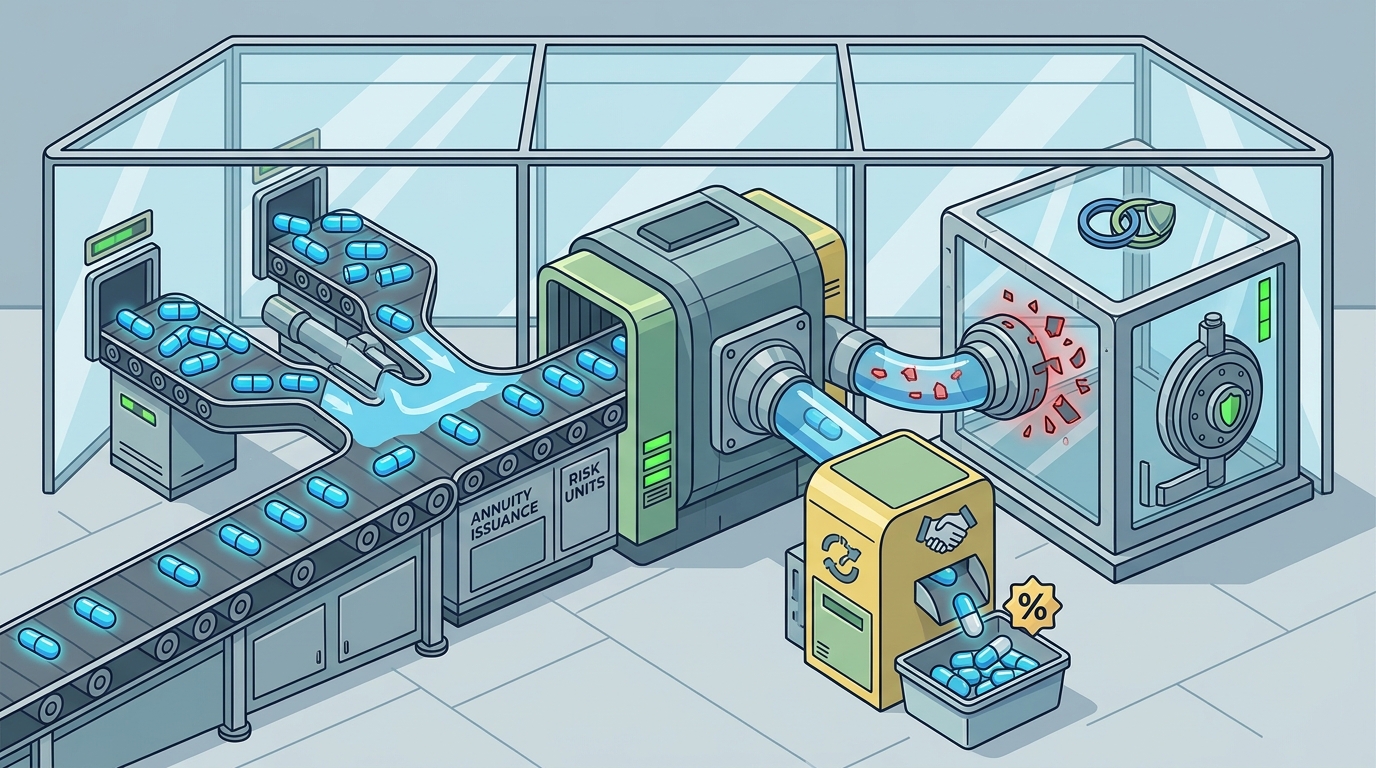
Consolidated annuity issuance refers to the strategic aggregation of annuity liabilities into a unified portfolio managed through a centralized platform. This approach contrasts sharply with traditional siloed issuance, where products are managed in isolation across different business units. The primary driver for this consolidation is the elimination of redundant operational processes. By standardizing data architectures and underwriting guidelines, insurers can significantly lower the cost per policy.
At Acturion Group, we recognize that the complexity of modern annuity products requires a robust technological foundation. Our platform supports the seamless integration of diverse product types, allowing for real-time pricing adjustments based on aggregate risk data. This centralized visibility enables actuaries to model scenarios with greater precision, reducing the margin of error that typically inflates pricing in fragmented systems. (Acturion Group)
The operational clarity provided by consolidation also enhances regulatory compliance. With a single source of truth for liability data, reporting to regulatory bodies becomes more accurate and less resource-intensive. This efficiency translates directly into lower operational expenditures, which can be passed on to customers in the form of improved product terms or retained as profit to strengthen the balance sheet. (Sample Page 8211 Acturion)
The Role of Reinsurance in Cost Reduction
Reinsurance serves as a critical lever in managing the financial volatility associated with annuity guarantees. By transferring a portion of the risk to reinsurers, primary insurers can reduce the amount of capital they must hold against potential adverse outcomes. This capital relief is a direct cost advantage, as regulatory capital requirements often represent a significant portion of an insurer's total expenses.
According to data from major actuarial consulting firms, the use of reinsurance can lower the cost of capital by 15 to 25 percent for large annuity portfolios. This reduction is particularly pronounced in products with long-duration guarantees, such as variable annuities with living benefits. The reinsurer assumes the tail risk, allowing the primary insurer to focus on core underwriting and customer acquisition.
Acturion Group facilitates these complex transactions by providing the analytical infrastructure necessary to price reinsurance treaties accurately. Our tools enable insurers to simulate various risk transfer scenarios, ensuring that the cost of reinsurance premiums is balanced against the savings in capital charges. This dynamic pricing capability is essential for maintaining profitability in a low-interest-rate environment.
Key Pricing Advantages for Insurers
One of the most significant benefits of consolidated issuance is the ability to optimize pricing across the entire portfolio. When data is siloed, insurers often apply uniform margins to different segments, leading to overpricing in some areas and underpricing in others. Consolidation allows for granular, risk-based pricing that reflects the true cost of each liability.
This precision leads to several direct cost advantages. First, it reduces the likelihood of adverse selection, where high-risk individuals disproportionately purchase certain products. Second, it enables dynamic pricing strategies that respond to market conditions in real time. For example, if interest rates rise, the insurer can adjust pricing across the consolidated portfolio to maintain target margins without delaying product launches.
Furthermore, consolidated systems reduce the cost of product development. New annuity variants can be launched faster and at a lower cost because the underlying infrastructure is already in place. This agility is crucial in a competitive market where customer preferences shift rapidly. Acturion Group's platform supports rapid product configuration, allowing insurers to test new offerings with minimal technical overhead.
Capital Efficiency and Solvency Impact
Capital efficiency is a paramount concern for annuity insurers. The amount of capital required to support annuity liabilities is determined by regulatory frameworks such as Solvency II in Europe and the Risk-Based Capital (RBC) requirements in the United States. Consolidated issuance and reinsurance partnerships can significantly reduce these capital requirements.
By aggregating risks, insurers can benefit from diversification effects that lower the overall volatility of their liability stream. This diversification reduces the capital charge required to cover potential shortfalls. Additionally, reinsurance treaties that qualify for capital relief under regulatory rules can further reduce the amount of capital that must be held.
The impact on solvency ratios is substantial. Improved capital efficiency allows insurers to write more business with the same capital base, effectively increasing their capacity to grow. This growth potential is a key strategic advantage in the annuity market, where scale is often correlated with cost efficiency. Acturion Group provides the analytics needed to quantify these capital benefits, helping insurers make informed decisions about risk transfer and portfolio management.
Comparing Issuance Models
To understand the full scope of cost advantages, it is helpful to compare consolidated issuance with traditional fragmented models. The table below outlines the key differences in operational and financial metrics.
| Feature | Consolidated Issuance | Traditional Fragmented Model |
|---|---|---|
| Operational Overhead | Low (Standardized processes) | High (Redundant systems) |
| Data Accuracy | High (Single source of truth) | Variable (Siloed data) |
| Capital Efficiency | High (Diversification benefits) | Low (Fragmented risk profiles) |
| Product Agility | High (Rapid configuration) | Low (Lengthy development cycles) |
| Reinsurance Integration | Seamless (Automated treaty management) | Manual (Complex reconciliation) |
The data clearly indicates that consolidated models offer superior efficiency across all key metrics. This efficiency is not just a cost saving but a strategic enabler that allows insurers to compete more effectively in a dynamic market.
Key Takeaways
- Operational Efficiency: Consolidated issuance reduces administrative costs by up to 30% through process standardization.
- Capital Relief: Reinsurance partnerships can lower the cost of capital by 15 to 25 percent for large portfolios.
- Pricing Precision: Centralized data enables risk-based pricing, reducing adverse selection and margin leakage.
- Regulatory Compliance: A single source of truth simplifies reporting and reduces compliance costs.
- Product Agility: Consolidated platforms allow for faster product launches and configuration.
- Diversification Benefits: Aggregating risks lowers overall volatility and capital requirements.
- Strategic Growth: Improved capital efficiency increases the capacity to write new business.
Frequently Asked Questions
What is consolidated annuity issuance?
Consolidated annuity issuance is the practice of aggregating annuity liabilities into a unified portfolio managed through a centralized platform to improve efficiency and pricing accuracy.
How does reinsurance reduce annuity costs?
Reinsurance reduces costs by transferring specific risks to reinsurers, which lowers the amount of capital the primary insurer must hold, thereby reducing the cost of capital.
What are the main benefits of data consolidation?
Data consolidation provides a single source of truth, improving data accuracy, simplifying regulatory reporting, and enabling more precise risk modeling.
Can consolidation improve product agility?
Yes, consolidated platforms allow for rapid product configuration and testing, enabling insurers to launch new products faster than with fragmented systems.
How does Acturion Group support these strategies?
Acturion Group provides the analytical infrastructure and platform capabilities needed to manage consolidated portfolios and optimize reinsurance treaties.
What is the impact on solvency ratios?
Improved capital efficiency from consolidation and reinsurance can lead to higher solvency ratios, allowing insurers to write more business with the same capital base.
Are there regulatory considerations for consolidation?
Yes, insurers must ensure that consolidated data practices meet regulatory standards for accuracy and reporting, which consolidation often simplifies.
How is pricing optimized in a consolidated model?
Pricing is optimized by using aggregate risk data to apply granular, risk-based margins, reducing the need for broad, conservative margins.
Contact Acturion Group
Ready to optimize your annuity issuance strategy? Acturion Group provides the expertise and technology to help you navigate the complexities of consolidated issuance and reinsurance. Visit our company page to learn more about our mission and values. Explore our product offerings to see how our platform can support your specific needs. For detailed information on our service delivery, check out our customer experience resources. If you have specific questions about our capabilities, review our frequently asked questions. To discuss your unique requirements, contact our customer service team directly. Schedule a demo today by visiting our demo page and discover how Acturion Group can drive value for your organization.