Step-by-Step Guide to Optimizing Annuity Portfolio Capital Efficiency
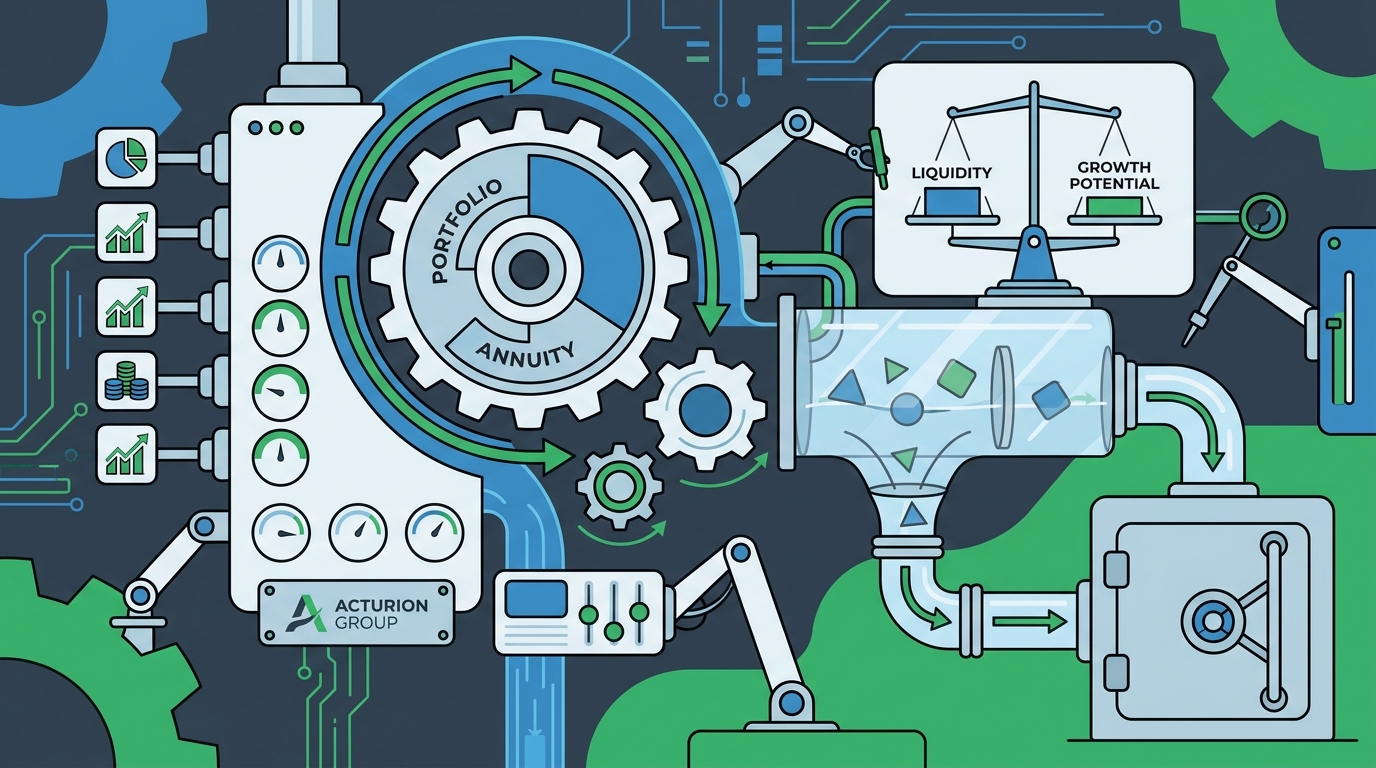
Capital efficiency in annuity portfolios is no longer a niche concern for high-net-worth individuals; it is a fundamental requirement for sustainable retirement income. According to recent industry analysis, inefficient capital allocation in fixed annuities can erode purchasing power by an average of 2 to 3 percent annually due to inflation and opportunity costs. This guide provides a rigorous, step-by-step framework to maximize the utility of your annuity holdings while maintaining liquidity and growth potential.
Understanding Capital Efficiency in Annuities
Before implementing changes, it is critical to define what capital efficiency means in the context of deferred annuities. Capital efficiency is the ratio of productive growth potential to the total capital deployed in an annuity contract. Many investors hold annuities with low interest rates or excessive fees that drag down overall portfolio performance. Optimizing this ratio involves identifying underperforming contracts and restructuring them to align with current market conditions and personal risk tolerance.
Acturion Group specializes in analyzing these ratios to ensure your retirement assets work harder. We help clients identify where capital is trapped in low-yield environments and provide pathways to redirect it toward more efficient vehicles. For a deeper understanding of how annuity structures impact long-term wealth, explore our comprehensive guide on annuity fundamentals.
Step 1: Audit Your Current Annuity Holdings
The first step in optimization is a forensic audit of your existing annuity portfolio. This process involves gathering all contract documents, including the original prospectus, latest statements, and rider summaries. You must identify the type of each annuity, whether it is a Fixed, Fixed-Indexed, or Variable annuity, as each has distinct optimization levers.
Key metrics to extract during this audit include:
- Current Credited Interest Rate: Compare this against current market indices for similar risk profiles.
- Accumulation Value vs. Premium Paid: Determine the total growth achieved to date.
- Rider Fees: Identify any annual fees for income riders or death benefit enhancements that may no longer provide value.
Without this data, any optimization strategy is based on guesswork. If you are unsure how to interpret your contract documents, our team at Acturion Group offers professional annuity analysis services to clarify your position.
Step 2: Evaluate Surrender Cost Schedules
Surrender charges are the primary barrier to liquidity in annuity contracts. These fees typically decline over time, often reaching zero after seven to ten years. However, some contracts have extended surrender periods or penalties that persist for decades. Understanding your specific surrender schedule is crucial before considering any changes.
If you are within the surrender period, calculate the net value of any potential exchange. The formula is simple: (Current Surrender Value minus Surrender Charge) minus New Contract Costs. If the result is negative or negligible, the cost of moving capital may outweigh the benefits of optimization. In such cases, holding the current contract may be the most efficient path.
For detailed information on how surrender periods impact liquidity, refer to this Investopedia guide on surrender charges.
Step 3: Execute Strategic 1035 Exchanges
A 1035 exchange allows you to swap one annuity contract for another without triggering immediate tax consequences. This is the primary tool for capital efficiency optimization. By exchanging a low-performing annuity for a higher-performing one, you can reset the interest crediting mechanism and potentially reduce fees.
However, not all 1035 exchanges are created equal. You must ensure that the new contract offers a tangible benefit, such as:
- Higher interest rates or index participation caps.
- Lower expense ratios or rider fees.
- Better death benefit options or inflation protection.
Acturion Group provides expert guidance on 1035 exchanges to ensure compliance and maximize the financial advantage of the swap. It is essential to work with a professional who understands the tax code intricacies to avoid unintended tax liabilities.
Step 4: Optimize Income Rider Structures
For many investors, the goal of an annuity is to generate guaranteed lifetime income. Income riders can significantly boost this income, but they come at a cost. Optimizing these riders involves balancing the premium cost against the projected income benefit.
Consider the following strategies:
- Step-Up Provisions: Choose riders that allow you to lock in growth periodically, resetting the income base without additional premiums.
- Enhanced Death Benefits: Evaluate if a higher death benefit rider justifies its cost based on your estate planning goals.
- Long-Term Care Integration: Some riders offer accelerated benefits for long-term care, which can be a critical component of comprehensive retirement planning.
Understanding the nuances of these riders is complex. For a detailed breakdown of income rider options, read our article on annuity income riders.
Step 5: Analyze Tax Implications and Deferral
One of the primary advantages of annuities is tax-deferred growth. However, withdrawals are taxed as ordinary income, which can be less efficient than capital gains treatment for other investments. Optimizing capital efficiency includes managing the timing and amount of withdrawals to minimize tax drag.
Strategies include:
- Qualified Longevity Annuity Contracts (QLACs): These allow you to defer required minimum distributions (RMDs) until age 85, reducing current taxable income.
- Systematic Withdrawals: Taking small, regular withdrawals can help manage tax brackets more effectively than large lump sums.
- Charitable Remainder Trusts: For high-net-worth individuals, integrating annuities with charitable trusts can provide tax deductions and income.
According to the Internal Revenue Service, proper planning around annuity distributions is essential to avoid excessive tax burdens in retirement.
Step 6: Manage Liquidity and Access Needs
Capital efficiency is not just about growth; it is also about access. An annuity that generates high returns but locks up capital for decades may not be efficient if you face unexpected liquidity needs. Ensure your portfolio includes a mix of annuities with varying surrender periods and liquidity features.
Consider the following liquidity options:
- Free Withdrawal Provisions: Most annuities allow penalty-free withdrawals of 10 percent of the premium annually.
- Partial Surrenders: Strategically surrendering small portions of the contract can provide cash flow without triggering full surrender charges.
- Living Benefit Riders: Some riders offer guaranteed withdrawal benefits that allow access to principal under specific conditions.
For more insights on managing liquidity in retirement, check out this Kiplinger article on annuity liquidity.
Key Takeaways
- Audit Regularly: Conduct a full audit of your annuity holdings every three to five years to identify underperforming contracts.
- Understand Surrender Charges: Always calculate the net value of any exchange after accounting for surrender fees and new contract costs.
- Leverage 1035 Exchanges: Use tax-free exchanges to move capital from low-yield to high-yield environments without tax penalties.
- Optimize Riders: Ensure income riders provide a clear benefit that justifies their annual cost.
- Manage Taxes: Utilize strategies like QLACs and systematic withdrawals to minimize ordinary income tax liability.
- Prioritize Liquidity: Balance growth potential with access needs to avoid liquidity traps in retirement.
- Seek Professional Advice: Annuity optimization is complex; work with experts like Acturion Group to navigate the landscape.
Frequently Asked Questions
What is the primary benefit of a 1035 exchange?
A 1035 exchange allows you to swap one annuity for another without triggering immediate tax consequences, enabling you to move capital to more efficient vehicles.
How do surrender charges impact capital efficiency?
Surrender charges reduce the net value of your annuity if you withdraw funds early, potentially making an exchange financially unviable until the charge period ends.
What is a Qualified Longevity Annuity Contract (QLAC)?
A QLAC is a type of deferred annuity that allows you to use up to 25 percent of your IRA assets to defer required minimum distributions until age 85.
Are annuity income riders worth the cost?
Income riders can be worth the cost if they provide guaranteed income that exceeds the premium paid, especially in low-interest-rate environments.
How often should I review my annuity portfolio?
It is recommended to review your annuity portfolio at least every three to five years, or whenever there are significant changes in interest rates or your personal financial situation.
Can I access my annuity funds without penalties?
Most annuities allow penalty-free withdrawals of 10 percent of the premium annually. Additional withdrawals may incur surrender charges and taxes.
What is the difference between fixed and variable annuities?
Fixed annuities offer guaranteed interest rates and principal protection, while variable annuities allow investment in sub-accounts with potential for higher returns and greater risk.
How does inflation affect annuity capital efficiency?
Inflation erodes the purchasing power of fixed annuity payments. Indexed annuities or riders with inflation protection can help mitigate this risk.
Optimize Your Annuity Portfolio Today
Optimizing your annuity portfolio requires careful analysis, strategic planning, and expert guidance. Acturion Group is dedicated to helping you maximize the efficiency of your retirement assets. Contact us today to schedule a consultation and take the first step toward a more efficient financial future. Visit our contact page to get started.