Annuity Portfolio Optimization: Cost-Benefit Analysis for Life Insurers
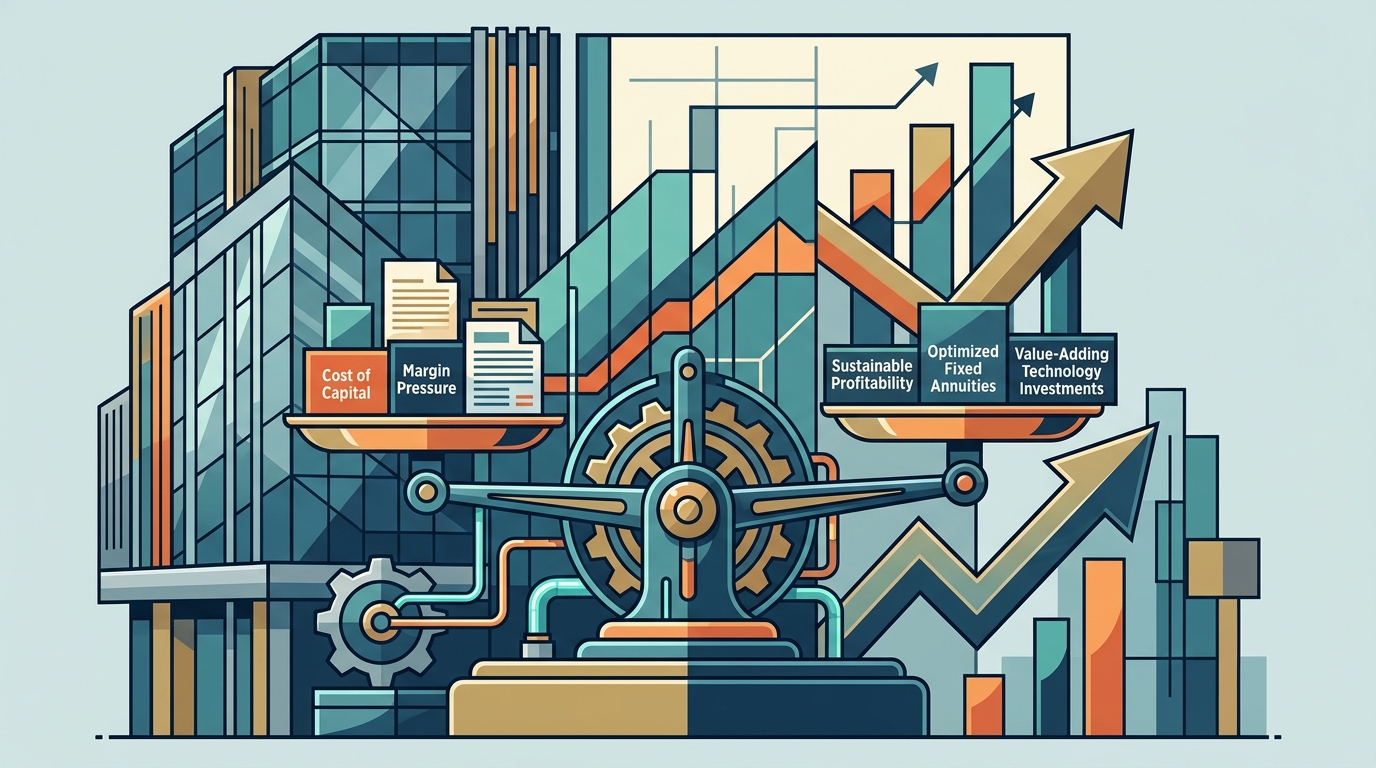
Life insurers managing fixed and fixed-indexed annuity books face unprecedented margin pressure due to shifting interest rate environments and regulatory scrutiny. According to recent industry data, the average cost of capital for annuity writers has increased by approximately 150 basis points over the last three years. This financial reality forces executives to evaluate every technology investment through a rigorous lens. The question is no longer just about compliance, but about sustainable profitability. This guide analyzes the cost-benefit dynamics of deploying advanced portfolio optimization platforms.
Understanding the Need for Optimization
Annuity portfolio optimization is the strategic process of managing the assets and liabilities of an insurance company to maximize returns while minimizing risk. It is a critical function for maintaining solvency and meeting policyholder obligations. As interest rates fluctuate, the duration mismatch between assets and liabilities becomes a primary source of financial instability.
Traditional methods of managing these books often rely on static hedging strategies. These approaches fail to capture the dynamic nature of policyholder behavior. For instance, surrender rates can spike during periods of market volatility. Without real-time data, insurers may hold insufficient hedges or over-hedge, leading to unnecessary costs. The integration of advanced analytics allows for dynamic hedging strategies that adjust to changing market conditions. (Sample Page 8211 Acturion)
Acturion Group provides specialized solutions that help insurers navigate these complexities. By leveraging advanced actuarial modeling, companies can better predict future cash flows and adjust their investment strategies accordingly. Visit our company page to learn more about our approach to actuarial science.
The Cost Structure of Legacy Systems
Implementing a new portfolio optimization platform involves significant upfront and ongoing costs. Understanding these costs is essential for a accurate cost-benefit analysis. The primary cost drivers include software licensing, implementation services, data infrastructure, and internal labor.
Software Licensing and Maintenance
Enterprise-grade optimization platforms typically operate on a subscription or perpetual license model. Annual maintenance fees often range from 15 to 20 percent of the initial license cost. These fees cover software updates, technical support, and access to new features. For large insurers with complex books, these costs can scale significantly based on the number of policies or assets under management.
Implementation and Integration
The most substantial cost often lies in implementation. Integrating an optimization engine with existing core systems, such as policy administration and general ledger platforms, requires extensive data mapping and testing. According to industry benchmarks, implementation projects can take between 6 to 12 months to complete. During this period, internal IT and actuarial teams must dedicate significant resources to ensure data integrity and system compatibility.
Data Infrastructure
Optimization platforms require high-quality, granular data. Many insurers must invest in data cleansing and enrichment projects before the new system can go live. This includes standardizing policy attributes, updating historical surrender data, and aligning asset allocation records. Failure to address data quality issues can lead to inaccurate optimization results and poor decision-making.
For more information on how we handle data integrity, explore our product offerings.
Quantifying the Benefits
The benefits of portfolio optimization extend beyond simple cost savings. They encompass improved risk management, enhanced regulatory compliance, and better capital allocation. Quantifying these benefits is crucial for justifying the investment to the board of directors.
Improved Risk Management
Advanced optimization platforms enable dynamic hedging strategies that respond to real-time market changes. This reduces the risk of margin erosion due to interest rate fluctuations. For example, a dynamic hedging strategy can adjust the duration of the asset portfolio to match the changing duration of the liability portfolio. This alignment minimizes the impact of interest rate shocks on the company's surplus.
Research indicates that insurers using dynamic hedging strategies experience up to 30 percent less volatility in their earnings compared to those using static strategies. This stability is valuable for maintaining investor confidence and meeting regulatory capital requirements.
Enhanced Capital Efficiency
Optimization platforms help insurers identify opportunities to reduce capital reserves. By accurately modeling the risks in their annuity books, companies can demonstrate to regulators that their capital levels are sufficient. This can lead to a reduction in the amount of capital held in reserve, freeing up resources for other strategic initiatives. According to recent regulatory updates, insurers that demonstrate robust risk management practices may benefit from lower capital charges.
Operational Efficiency
Automating the optimization process reduces the manual effort required by actuarial and finance teams. This allows staff to focus on higher-value activities, such as strategic planning and product development. Automation also reduces the risk of human error, which can be costly in complex financial calculations.
Learn about our customer service support for ongoing optimization needs.
Building the ROI Framework
To determine the viability of an optimization platform, insurers must build a comprehensive Return on Investment (ROI) framework. This framework should include both tangible and intangible benefits.
Tangible Benefits
Tangible benefits are those that can be directly measured in financial terms. These include:
- Reduced Hedging Costs: Savings from more efficient asset allocation and reduced trading costs.
- Lower Capital Requirements: Savings from reduced capital reserves due to improved risk modeling.
- Operational Savings: Reduction in labor costs due to automation of manual processes.
Intangible Benefits
Intangible benefits are harder to quantify but are equally important. These include:
- Improved Decision-Making: Better insights into risk and return drivers.
- Regulatory Compliance: Reduced risk of regulatory penalties and fines.
- Competitive Advantage: Ability to offer more competitive products due to lower costs.
For insights into our strategic partnerships, visit our special sales page.
Platform Comparison Matrix
When evaluating portfolio optimization platforms, it is helpful to compare key features and capabilities. The following table summarizes the typical characteristics of leading solutions in the market.
| Feature | Legacy Systems | Modern Optimization Platforms | Acturion Group Solution |
|---|---|---|---|
| Hedging Strategy | Static | Dynamic | Dynamic & Adaptive |
| Data Granularity | Low | High | High |
| Integration Complexity | High | Medium | Low |
| Regulatory Reporting | Manual | Automated | Automated |
| Scalability | Limited | High | High |
For detailed product specifications, check our products section.
Key Takeaways
- Cost of Inaction: The cost of maintaining legacy systems often exceeds the cost of new technology due to inefficiencies and risk exposure.
- Dynamic Hedging: Dynamic hedging strategies can reduce earnings volatility by up to 30 percent compared to static approaches.
- Capital Efficiency: Improved risk modeling can lead to significant reductions in required capital reserves.
- Data Quality: High-quality data is the foundation of successful optimization. Invest in data cleansing early.
- Implementation Timeline: Plan for a 6 to 12 month implementation period to ensure smooth integration.
- ROI Measurement: Include both tangible and intangible benefits in your ROI calculation.
- Strategic Alignment: Ensure the chosen platform aligns with your long-term strategic goals.
Frequently Asked Questions
What is the typical implementation timeline for an annuity optimization platform?
Implementation timelines typically range from 6 to 12 months, depending on the complexity of the existing IT infrastructure and the volume of data to be migrated.
How do optimization platforms improve capital efficiency?
By providing more accurate risk models, optimization platforms allow insurers to reduce the amount of capital held in reserve, freeing up resources for other uses.
What are the main risks of not optimizing an annuity portfolio?
Key risks include margin erosion due to interest rate fluctuations, increased regulatory scrutiny, and operational inefficiencies that lead to higher costs.
How does Acturion Group support clients during implementation?
Acturion Group provides comprehensive support, including data analysis, system configuration, and ongoing training, to ensure a smooth transition.
Can optimization platforms handle complex product structures?
Yes, modern platforms are designed to handle a wide range of product structures, including fixed, fixed-indexed, and variable annuities.
What role does data quality play in optimization?
Data quality is critical. Inaccurate data can lead to incorrect optimization results, which can have significant financial consequences.
How is the ROI of an optimization platform calculated?
ROI is calculated by comparing the total cost of ownership against the tangible and intangible benefits, such as reduced hedging costs and improved capital efficiency.
Next Steps
Optimizing your annuity portfolio is a strategic imperative in today's volatile market. Acturion Group is ready to help you navigate this complex landscape. Contact us today to schedule a consultation and discover how our solutions can drive value for your organization. Visit our homepage to get started.