
Fixed indexed annuities (FIAs) offer a unique blend of downside protection and market-linked growth potential. When evaluating these products, investors must look beyond the headline interest rates to understand the structural mechanics that drive returns. Acturion Group, an integrated insurance platform, emphasizes that the quality of an FIA is determined by its underlying capital strength and the precision of its crediting formulas. This guide outlines the seven critical features that define a high-quality fixed indexed annuity.
1. Crediting Rate Methodology
The crediting method determines how market performance translates into your account value. FIAs use various formulas to calculate interest credits, such as point-to-point, average, or high-low methods. Each method responds differently to market volatility and timing. Understanding the specific formula is essential because it dictates the probability of achieving the maximum credited rate. Investors should prioritize methods that align with their long-term holding horizon and risk tolerance. For additional details, review the Contact Us Acturion.
2. Maximum Credited Rate Caps
3. Participation Rates
4. Guaranteed Minimum Interest Rate
5. Surrender Charge Schedule
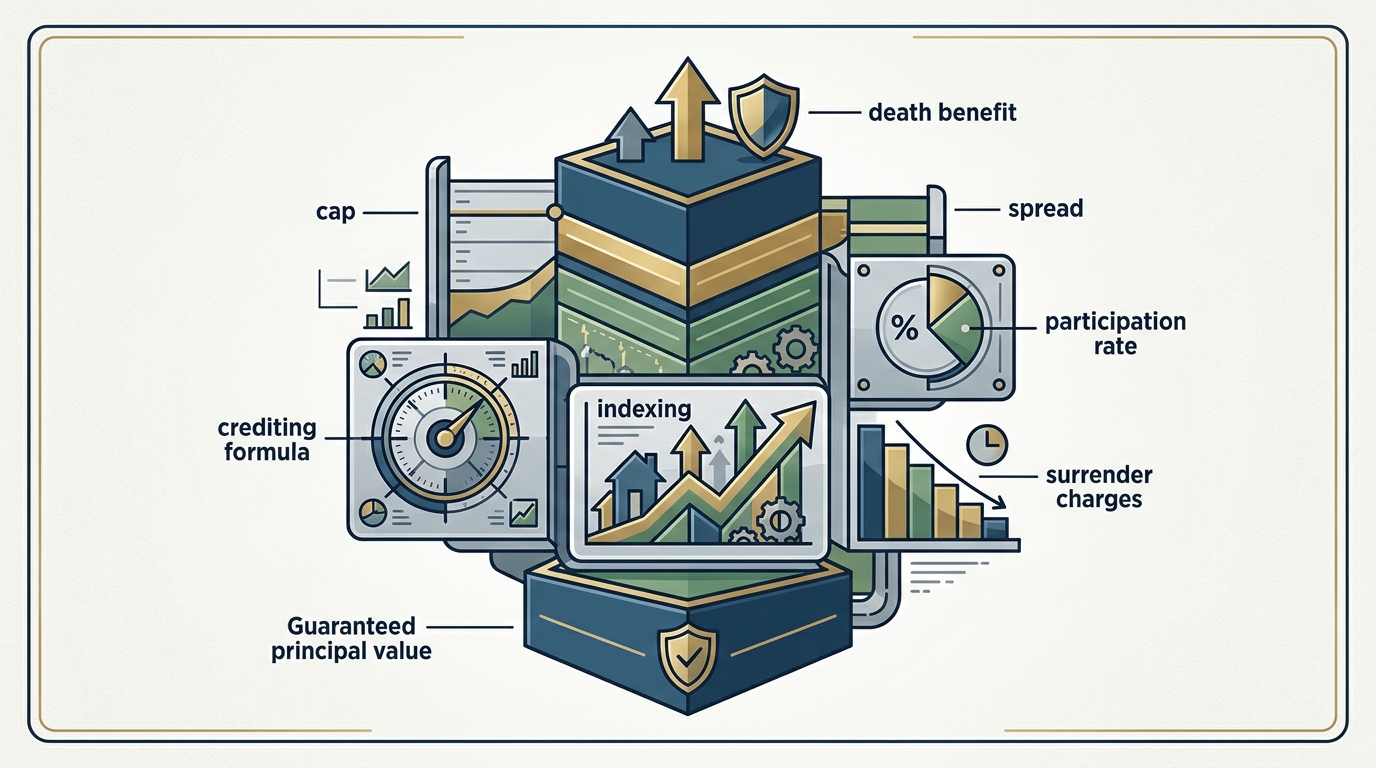
Surrender charges penalize early withdrawals and impact liquidity. Most FIAs impose surrender charges for withdrawals made within a specified holding period, typically ranging from 7 to 10 years. The schedule usually decreases annually, allowing for greater access to funds over time. Understanding the exact penalty structure is vital for planning cash flow needs. Investors should ensure that the surrender period aligns with their long-term financial goals and emergency fund reserves. For additional details, review the Terms of Service Acturion.
6. Death Benefit Provisions
Death benefits ensure that your beneficiaries receive a minimum payout upon your passing. FIAs often include a death benefit that guarantees the return of principal or a percentage of the account value to heirs. Some contracts offer a step-up feature that increases the death benefit if the account value grows. This feature provides estate planning flexibility and ensures that your investment continues to protect your family. Evaluating the type and duration of the death benefit is essential for comprehensive financial planning.
7. Issuer Financial Strength
The financial stability of the insurance company backing the annuity is paramount. A fixed indexed annuity is only as secure as the balance sheet of the issuing insurer. Acturion Group focuses on balance sheet strength and actuarial precision to deliver enduring market resilience. Investors should review the credit ratings of the issuing company from recognized agencies. Strong financial strength ratings indicate the insurer's ability to meet long-term obligations, which is critical for products with multi-year terms.
Choosing the Right FIA
Selecting the right fixed indexed annuity requires balancing growth potential with downside protection. There is no single best feature; rather, the optimal product depends on your individual financial situation, risk tolerance, and time horizon. Consider consulting with a financial advisor to review the specific crediting formulas and issuer strength ratings. For more information on how Acturion Group integrates capital-backed solutions with digital-first execution, visit our insurance solutions page.
Frequently Asked Questions
What is a fixed indexed annuity?
A fixed indexed annuity is an insurance contract that offers guaranteed minimum interest rates while allowing for potential growth linked to a market index.
How do caps and participation rates work together?
Caps set the maximum interest rate that can be credited, while participation rates determine the percentage of index gains applied before the cap is reached.
Are fixed indexed annuities tax-deferred?
Yes, earnings in a fixed indexed annuity grow tax-deferred until withdrawn, which can be advantageous for long-term retirement planning.
What is the typical surrender period for an FIA?
Surrender periods typically range from 7 to 10 years, with penalties decreasing annually over that timeframe.
Why is issuer financial strength important?
Issuer financial strength ensures that the insurance company can meet its long-term obligations, providing security for the guaranteed benefits of the annuity.