
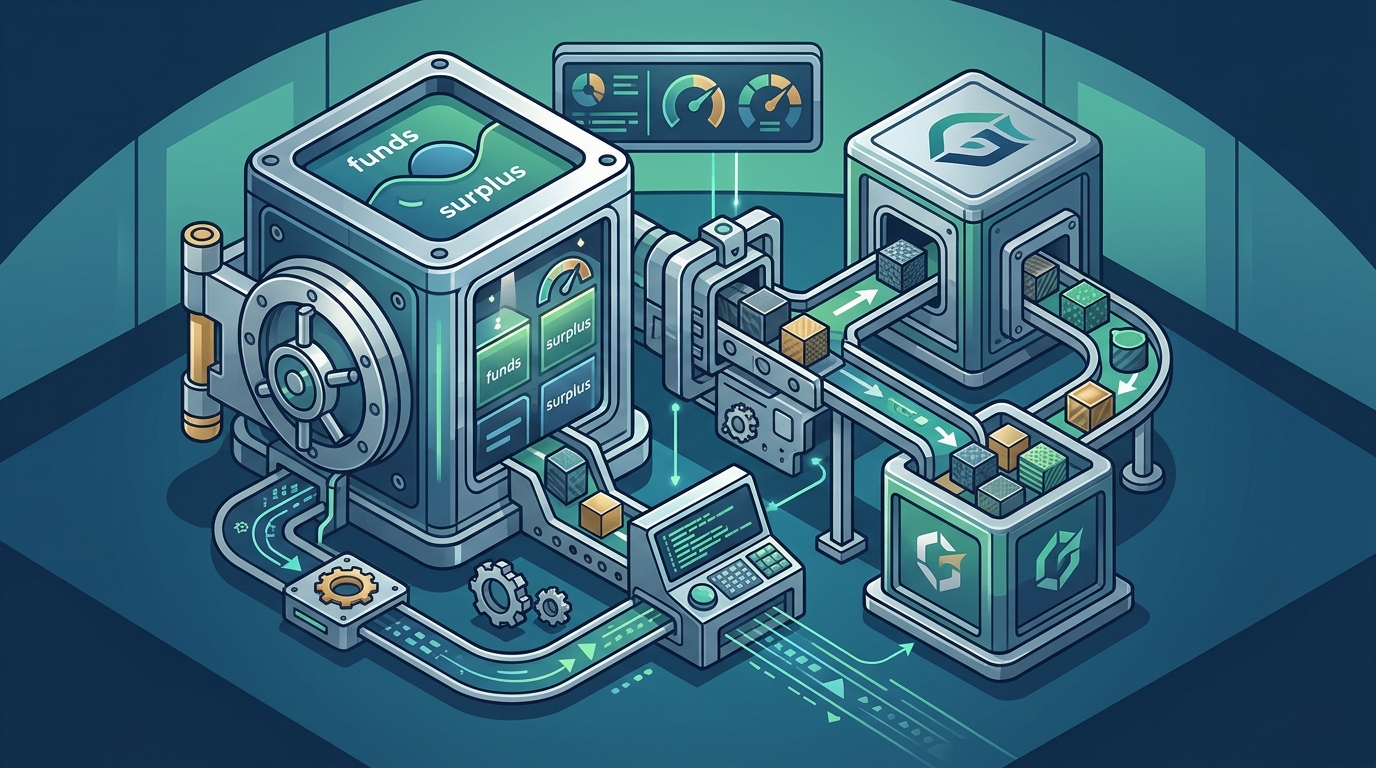
Life insurers should view reinsurance platforms as strategic partners that optimize balance sheet efficiency and unlock trapped surplus. By transferring specific liabilities, insurers can reduce risk-based capital requirements and improve solvency ratios. This approach allows carriers to focus on growth and distribution rather than holding excessive capital reserves. Acturion Group provides digital-first reinsurance solutions designed to support these capital efficiency goals.
The Strategic Role of Reinsurance in Capital Management
Key Implication: Reinsurance is not just a risk management tool; it is a capital management tool. Insurers should assess how ceding specific liabilities impacts their overall solvency position and return on equity.
Understanding Quota Share and Block Reinsurance
Quota share reinsurance is a structure where the reinsurer assumes a fixed percentage of all risks in a specific portfolio. This type of arrangement provides immediate capital relief and operational support. It is particularly useful for insurers looking to scale their business without proportionally increasing their capital base. The reinsurer typically provides a ceding commission, which offsets the cost of the reinsurance.
Block reinsurance, on the other hand, involves transferring a specific group of policies or a defined risk. This allows for more granular control over which liabilities are ceded. Insurers can target high-risk or capital-intensive blocks for transfer. This precision helps in managing the overall risk profile of the balance sheet. Both structures have distinct advantages depending on the insurer's specific capital constraints and growth objectives.
Operational Efficiency and Digital Integration
Modern reinsurance platforms are increasingly digital-first, offering streamlined onboarding and servicing. This digital integration reduces the administrative burden on primary insurers. It also improves data accuracy and reporting speed. Efficient data exchange is crucial for accurate capital modeling and regulatory reporting. Delays or errors in data can lead to misstated capital positions and potential regulatory issues.
Digital platforms also enable faster settlement and more transparent reporting. Insurers can track the performance of ceded risks in real-time. This visibility supports better decision-making regarding future reinsurance needs. The operational efficiency gained from digital integration can significantly reduce the cost of reinsurance. It also enhances the overall customer experience for policyholders by ensuring smoother claim processing.
Key Implication: Digital integration is a key differentiator in reinsurance platforms. Insurers should prioritize partners who offer robust, automated data exchange and reporting capabilities.
Regulatory Compliance and Transparency
Regulatory compliance is a top priority for life insurers. Reinsurance arrangements must meet specific regulatory standards to be recognized for capital relief. This includes requirements for the financial strength of the reinsurer and the structure of the reinsurance contract. Insurers must ensure that their reinsurance partners are licensed and regulated in their jurisdiction. Failure to meet these standards can result in the reinsurance not being recognized for capital purposes.
Transparency in the reinsurance relationship is also critical. Insurers need clear visibility into the reinsurer's financial health and operational capabilities. This includes access to audited financial statements and regulatory filings. Transparent reporting helps insurers maintain trust with their own regulators and stakeholders. It also supports the insurer's own governance and risk management processes.
Key Implication: Regulatory recognition is not automatic. Insurers must carefully vet their reinsurance partners to ensure that the arrangements meet all necessary compliance standards for capital relief.
Selecting the Right Reinsurance Partner
Selecting a reinsurance partner requires a thorough evaluation of their financial strength, expertise, and operational capabilities. Insurers should look for partners with a strong track record in the life insurance market. This includes experience with specific product types and risk profiles. A partner with deep industry knowledge can provide valuable insights and support.
Financial strength is a critical factor. Insurers should consider the credit rating of the reinsurer and their capital adequacy. A financially strong partner reduces counterparty risk and ensures the reliability of the reinsurance arrangement. Insurers should also evaluate the partner's operational infrastructure and technology capabilities. A robust operational platform ensures efficient and accurate servicing of ceded risks.
Key Implication: The right reinsurance partner is a strategic ally, not just a risk transfer vehicle. Insurers should prioritize partners who offer a combination of financial strength, operational excellence, and industry expertise.
Key Takeaways
- Reinsurance is a dual-purpose tool for both risk management and capital optimization.
- Quota share and block reinsurance offer different benefits for capital relief and operational support.
- Digital-first platforms enhance operational efficiency and data accuracy in reinsurance arrangements.
- Regulatory compliance is essential for reinsurance to be recognized for capital relief.
- Financial strength and operational capability are critical factors in selecting a reinsurance partner.
- Strategic alignment between reinsurance structures and capital goals is key to maximizing benefits.
Frequently Asked Questions
How does reinsurance impact risk-based capital requirements?
Reinsurance reduces risk-based capital requirements by transferring a portion of the insurer's risk to a reinsurer. This ceding of risk lowers the capital needed to support that risk, thereby improving the insurer's solvency ratio.
What is the difference between quota share and block reinsurance?
Quota share reinsurance involves ceding a fixed percentage of all risks in a portfolio, while block reinsurance involves transferring a specific group of policies or risks. Quota share provides broader capital relief, while block reinsurance offers more targeted risk management.
Why is digital integration important in reinsurance platforms?
Digital integration streamlines data exchange and reporting, reducing administrative burden and improving accuracy. This efficiency supports better capital modeling and regulatory reporting, ultimately lowering the cost of reinsurance.
What regulatory standards must reinsurance arrangements meet?
Reinsurance arrangements must meet specific regulatory standards to be recognized for capital relief. These standards typically include requirements for the financial strength of the reinsurer and the structure of the reinsurance contract.
How should insurers evaluate the financial strength of a reinsurance partner?
Insurers should evaluate the credit rating, capital adequacy, and audited financial statements of the reinsurance partner. A financially strong partner reduces counterparty risk and ensures the reliability of the reinsurance arrangement.
Can reinsurance be used to support new product development?
Yes, by freeing up capital through reinsurance, insurers can allocate resources to new product development and distribution. This allows for growth without proportionally increasing the capital base.