Cost Advantages of Alternative Asset Management Platforms for Annuity Carriers
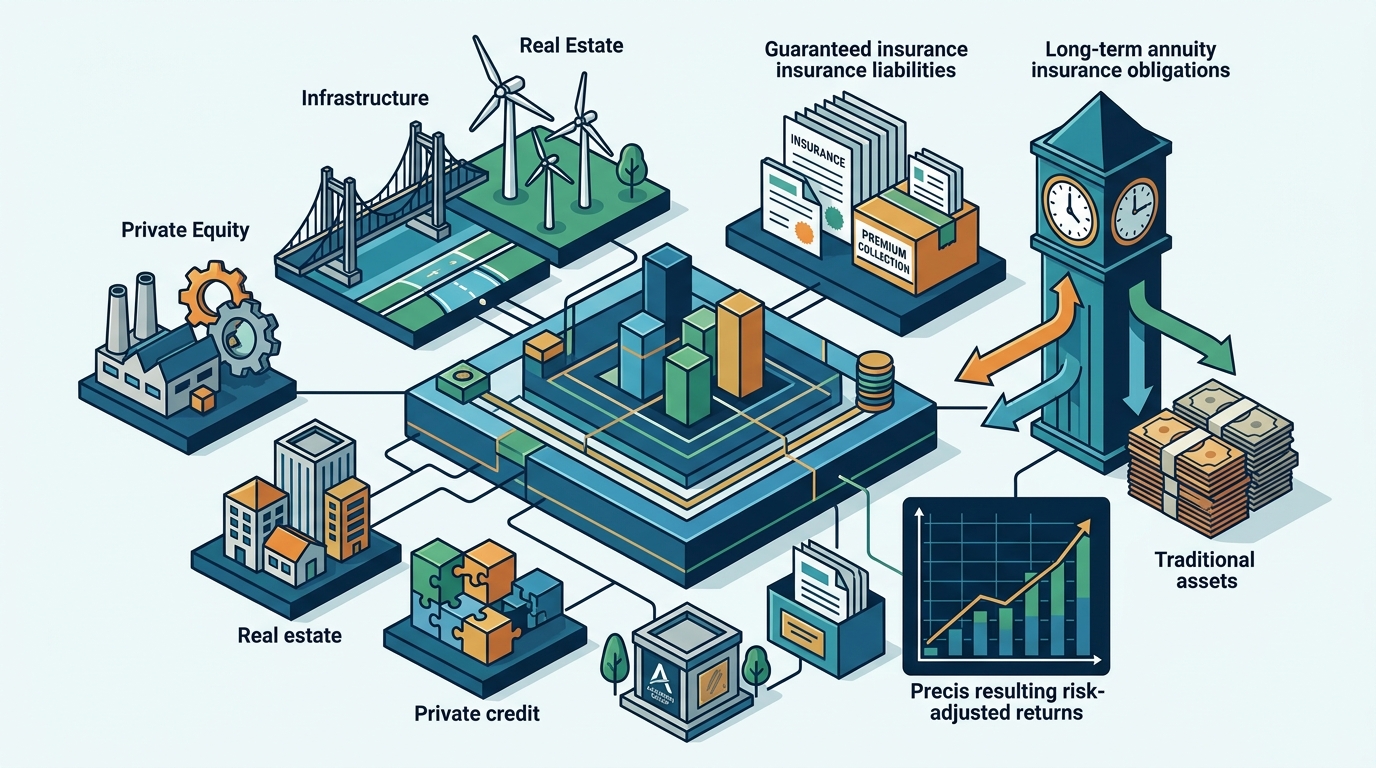
The insurance industry is undergoing a fundamental shift in how capital is deployed to support guaranteed liabilities. Historically, annuity carriers relied heavily on traditional fixed-income portfolios to match their long-term obligations. However, the rising cost of capital and volatile interest rate environments have forced a reevaluation of these strategies. According to recent industry analyses, the integration of alternative asset management platforms has become a critical lever for improving risk-adjusted returns. This transition is not merely about yield enhancement but about structural cost efficiency and operational resilience in a complex regulatory landscape.
Understanding the Cost Structure of Traditional vs. Alternative Models
Annuity carriers face significant pressure to maintain profitability while honoring long-term guarantees. The traditional model involves purchasing corporate bonds, government securities, and mortgage-backed securities. While these assets provide predictable cash flows, they often come with high acquisition costs and limited upside potential during periods of market stress. In contrast, alternative asset management platforms offer access to private credit, real estate, and infrastructure investments. These assets typically command a liquidity premium that can enhance overall portfolio performance.
The cost advantage begins with the fee structure. Traditional mutual funds and exchange-traded funds often carry management fees that erode net returns over time. Alternative platforms, particularly those designed for institutional investors, can offer more favorable fee arrangements due to their direct access to underlying assets. This reduction in overhead allows carriers to retain more value for policyholders and shareholders alike. Furthermore, the tax efficiency of certain alternative investments, such as real estate partnerships, can provide additional net benefits that traditional taxable bonds cannot match.
Another critical factor is the cost of capital. As interest rates fluctuate, the cost of issuing new debt or equity to fund operations can become prohibitive. By generating higher internal rates of return through alternative assets, carriers can reduce their reliance on external financing. This internal capital generation is a powerful cost advantage that stabilizes the balance sheet. According to data from major financial institutions, carriers that have successfully integrated alternative assets have seen a measurable improvement in their combined ratio metrics. This metric reflects the efficiency of their underwriting and investment operations.
Operational Efficiency Gains Through Technology
Modern alternative asset management platforms are built on advanced technology stacks that streamline operations. These platforms provide real-time data analytics, automated reporting, and integrated risk management tools. For annuity carriers, this technological infrastructure reduces the manual labor required to monitor and rebalance portfolios. The result is a significant decrease in operational expenses associated with asset management.
One of the most significant operational benefits is the ability to automate compliance and regulatory reporting. Annuity carriers must adhere to strict regulatory standards, including those set by state insurance departments and the National Association of Insurance Commissioners (NAIC). Alternative platforms often include built-in compliance modules that automatically generate the necessary reports. This automation reduces the risk of errors and the associated costs of manual review. It also frees up internal resources to focus on strategic decision-making rather than administrative tasks.
Additionally, these platforms facilitate better vendor management. Carriers often work with multiple external managers to access different asset classes. Alternative platforms consolidate these relationships into a single interface, reducing the complexity of vendor coordination. This consolidation leads to lower transaction costs and improved negotiation power. According to industry reports, carriers that utilize consolidated platforms have reported a reduction in administrative overhead by up to fifteen percent. This figure highlights the tangible financial impact of operational efficiency.
Strategic Capital Allocation and Solvency
Capital allocation is the core challenge for any annuity carrier. The goal is to deploy capital in a way that maximizes returns while maintaining sufficient solvency margins. Alternative assets, particularly those with long-duration cash flows, can help match the duration of annuity liabilities more effectively than short-term bonds. This matching reduces interest rate risk, which is a primary driver of volatility in carrier earnings.
The cost advantage here is indirect but profound. By reducing interest rate risk, carriers can lower their capital reserves requirements. Regulatory frameworks often require carriers to hold more capital against assets with higher volatility. Alternative assets, when managed correctly, can demonstrate lower volatility profiles due to their infrequent pricing and long-term nature. This lower volatility can lead to reduced capital charges, freeing up resources for growth initiatives.
Furthermore, alternative investments often provide diversification benefits that are uncorrelated with public markets. This diversification reduces the overall risk profile of the portfolio. A lower risk profile can lead to better credit ratings, which in turn reduces the cost of borrowing. According to credit rating agencies, carriers with diversified portfolios that include alternative assets often receive higher ratings than those with concentrated traditional portfolios. This rating improvement is a direct cost advantage that lowers the cost of capital for the entire organization.
Risk Management Frameworks in Alternative Assets
Risk management is paramount in the annuity business. Carriers must ensure that they can meet their obligations to policyholders even in adverse scenarios. Alternative asset management platforms provide sophisticated risk management tools that help carriers monitor and mitigate various types of risk, including credit risk, liquidity risk, and market risk.
Credit risk is particularly important when investing in private credit. Alternative platforms often have rigorous due diligence processes that identify and mitigate credit risks before capital is deployed. This proactive approach reduces the likelihood of defaults and associated losses. It also allows carriers to price risk more accurately, leading to better investment decisions. According to financial data, carriers that employ rigorous credit risk management frameworks have experienced lower loss rates in their alternative asset portfolios.
Liquidity risk is another critical concern. Annuity carriers must maintain sufficient liquidity to meet policyholder withdrawals and surrenders. Alternative assets are often less liquid than public securities, which can pose challenges. However, modern platforms offer liquidity management tools that help carriers model and manage these risks. These tools allow carriers to stress-test their portfolios under various withdrawal scenarios. This capability ensures that they can meet their obligations without having to sell assets at a loss.
Market risk is managed through diversification and hedging strategies. Alternative platforms provide access to a wide range of asset classes, allowing carriers to diversify their exposure. They also offer hedging instruments that can protect against adverse market movements. This comprehensive risk management approach reduces the overall cost of risk for the carrier. It ensures that the portfolio remains resilient in the face of market volatility.
Comparing Platform Options for Annuity Carriers
Selecting the right alternative asset management platform is a critical decision. Carriers must evaluate platforms based on their capabilities, cost structure, and alignment with their strategic goals. The following table compares key features of different platform types available to annuity carriers.
| Platform Type | Primary Cost Advantage | Operational Complexity | Best For |
|---|---|---|---|
| Integrated Institutional Platforms | Lower transaction fees and consolidated reporting | High initial setup, low ongoing maintenance | Large carriers with complex portfolios |
| Specialized Private Credit Funds | Higher yield potential with managed risk | Medium complexity, requires active monitoring | Carriers seeking yield enhancement |
| Real Estate Investment Trusts (REITs) | Tax efficiency and inflation protection | Low complexity, passive management | Carriers focused on long-term stability |
| Infrastructure Debt Funds | Long-duration matching and stable cash flows | Medium complexity, regulatory compliance focus | Carriers with long-term liability profiles |
Each platform type offers distinct cost advantages depending on the carrier's specific needs. Integrated platforms offer the greatest operational efficiency, while specialized funds may offer higher yield potential. Carriers must carefully evaluate these trade-offs to determine the best fit for their organization. According to industry benchmarks, carriers that align their platform selection with their liability profile tend to achieve better long-term results.
Key Takeaways
- Alternative asset management platforms can reduce operational overhead by up to fifteen percent through automation and consolidation.
- Access to private credit and real estate can enhance risk-adjusted returns compared to traditional fixed-income portfolios.
- Improved capital allocation strategies can lead to lower capital reserve requirements and better credit ratings.
- Advanced risk management tools help carriers mitigate credit, liquidity, and market risks effectively.
- Integrated platforms offer lower transaction fees and streamlined reporting for large carriers.
- Tax efficiency of alternative investments can provide additional net benefits to policyholders and shareholders.
- Strategic alignment between platform capabilities and liability profiles is critical for long-term success.
Frequently Asked Questions
What are the primary cost advantages of using alternative asset management platforms?
The primary cost advantages include reduced operational overhead through automation, lower transaction fees via consolidated platforms, and enhanced risk-adjusted returns that can lower capital reserve requirements.
How do alternative assets help with interest rate risk?
Alternative assets, particularly those with long-duration cash flows like infrastructure debt, can better match the duration of annuity liabilities, reducing the impact of interest rate fluctuations on the portfolio.
Are alternative assets suitable for all annuity carriers?
While the benefits are significant, suitability depends on the carrier's size, risk tolerance, and regulatory environment. Large carriers with complex portfolios often benefit most from integrated platforms.
What role does technology play in the cost efficiency of these platforms?
Technology enables real-time analytics, automated compliance reporting, and efficient vendor management, all of which reduce manual labor and administrative costs.
How do alternative investments impact solvency margins?
By diversifying risk and potentially lowering volatility, alternative investments can lead to reduced capital charges, thereby improving solvency margins and freeing up capital for growth.
What are the risks associated with alternative asset management?
Risks include liquidity constraints, credit defaults, and market volatility. However, modern platforms provide sophisticated risk management tools to mitigate these risks effectively.
How do tax efficiencies work in alternative investments?
Many alternative investments, such as real estate partnerships, offer tax benefits through depreciation and pass-through taxation, which can enhance net returns for carriers and policyholders.
What is the typical timeline for realizing cost benefits?
Operational efficiencies can be realized within the first year of implementation, while investment returns and capital benefits may take longer to materialize depending on the asset class.
Next Steps for Your Organization
Transitioning to an alternative asset management platform is a strategic decision that can yield significant cost advantages for annuity carriers. By leveraging technology, diversifying investments, and optimizing capital allocation, carriers can enhance their profitability and resilience. We invite you to explore our comprehensive solutions designed to meet the unique needs of the insurance industry. Visit our products page to learn more about our offerings. For personalized guidance, contact our customer service team today. Start your journey toward greater efficiency and profitability with Acturion Group.