Evaluation Criteria for Selecting an Alternative Asset Management Platform for Annuity Carriers
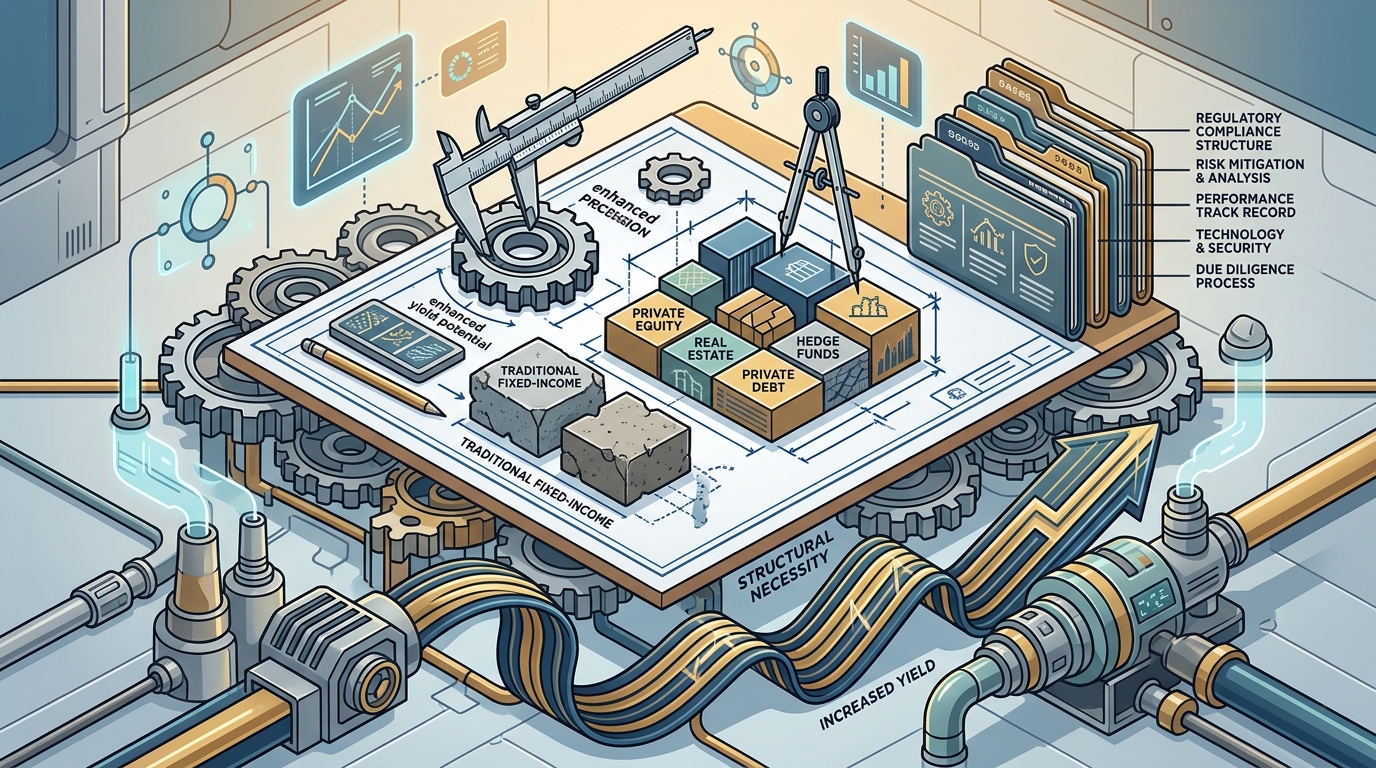
The landscape of fixed annuity products is undergoing a seismic shift. Traditional fixed-income strategies are no longer sufficient to meet the yield expectations of modern policyholders. According to recent industry reports, over 60% of annuity carriers are now actively exploring alternative asset classes to enhance portfolio performance. This transition is not merely a trend but a structural necessity driven by prolonged low-interest-rate environments and increased regulatory scrutiny on reserve adequacy. Selecting the right technology partner is the critical first step in this transformation. The platform you choose will dictate your ability to scale, manage risk, and deliver competitive products to the market.
Understanding Alternative Assets in Annuity Portfolios
Alternative assets refer to investment vehicles that fall outside the traditional categories of stocks, bonds, and cash. For annuity carriers, this typically includes private credit, real estate, infrastructure debt, and private equity. These assets offer higher potential yields and diversification benefits but come with unique liquidity and valuation challenges. Private credit is a lending market where loans are provided by non-bank lenders to companies that cannot access public debt markets. This asset class has become particularly attractive for annuity carriers due to its floating-rate nature, which provides a natural hedge against interest rate volatility.
The integration of these assets requires a fundamental change in how carriers manage their balance sheets. Traditional core systems are often ill-equipped to handle the complex cash flow patterns, illiquidity discounts, and fair value measurements associated with alternative investments. Carriers must evaluate whether their current infrastructure can support the granular data requirements demanded by regulators and rating agencies. The failure to adapt can result in reserve shortfalls and an inability to price products competitively.
Core Evaluation Criteria for Platform Selection
When evaluating potential platforms, carriers must look beyond surface-level features. The decision impacts long-term strategic agility and operational efficiency. The following criteria form the foundation of a robust selection process.
1. Asset Class Support and Flexibility
The platform must support a wide range of alternative asset classes without requiring extensive custom development. Look for pre-built connectors for private markets data providers and standardized workflows for common transaction types. Rigidity in asset support will force carriers to build costly workarounds, increasing technical debt and time-to-market.
2. Valuation Methodology Accuracy
Accurate valuation is paramount for financial reporting and reserve calculations. The platform should support multiple valuation methodologies, including discounted cash flow, comparable company analysis, and third-party appraisals. It must also handle the nuances of mark-to-model versus mark-to-market accounting standards. Fair value measurement is the process of estimating the price that would be received to sell an asset in an orderly transaction between market participants. The system must automate the aggregation of these values while maintaining a clear audit trail for every input and assumption.
3. Liquidity Management Capabilities
Annuity carriers face significant liquidity risk when policyholders surrender their contracts. The platform must provide real-time visibility into the liquidity profile of the alternative asset portfolio. This includes tracking lock-up periods, redemption gates, and notice requirements. Advanced liquidity forecasting tools are essential for ensuring that the carrier can meet policyholder obligations without forced sales of illiquid assets at unfavorable prices.
Technology Infrastructure and Integration
The technological backbone of the platform determines its scalability and reliability. Annuity carriers operate in a highly regulated environment where system downtime can have severe reputational and financial consequences.
API-First Architecture
A modern platform must offer a robust API-first architecture. This allows for seamless integration with existing core systems, general ledgers, and reporting tools. Open APIs enable carriers to build a best-of-breed ecosystem rather than being locked into a monolithic suite. This flexibility is crucial for adapting to future regulatory changes or business model shifts.
Data Integrity and Governance
Alternative asset data is often unstructured and sourced from multiple providers. The platform must have strong data governance capabilities to cleanse, normalize, and validate incoming data. Data lineage tracking is essential for tracing every data point back to its original source. This ensures that the carrier can defend its financial reports during regulatory audits. According to industry benchmarks, carriers with strong data governance frameworks reduce audit findings by up to 40%.
Risk Management and Regulatory Compliance
Regulatory scrutiny on alternative assets is intensifying. Carriers must demonstrate that their investment strategies align with their risk appetite and regulatory capital requirements.
Regulatory Reporting Automation
The platform should automate the generation of regulatory reports, such as those required by the NAIC (National Association of Insurance Commissioners). This includes detailed breakdowns of asset classes, valuation methods, and liquidity profiles. Manual reporting processes are prone to errors and are increasingly unsustainable as regulatory complexity grows.
Stress Testing and Scenario Analysis
Carriers must be able to run sophisticated stress tests on their alternative asset portfolios. The platform should allow for the simulation of various economic scenarios, such as interest rate shocks, credit downgrades, or liquidity dry-ups. This capability is critical for determining the impact on reserves and capital adequacy. Stress testing is the practice of subjecting a financial model to extreme but plausible market conditions to assess its resilience. The ability to perform these tests quickly and accurately is a key differentiator among platform providers.
Vendor Viability and Strategic Partnership
Selecting a platform is not just a technology purchase; it is a strategic partnership. The vendor must have the financial stability and industry expertise to support the carrier over the long term.
Industry Expertise and Support
The vendor should have a proven track record in the insurance industry, specifically with annuity carriers. They must understand the unique regulatory and operational challenges faced by the sector. Look for vendors who offer dedicated support teams with deep domain knowledge. This ensures that the carrier receives guidance on best practices and regulatory changes, not just technical support.
Implementation Timeline and Cost
Consider the total cost of ownership, including implementation, licensing, and ongoing maintenance. While cost is a factor, it should not be the primary driver. A cheaper platform that lacks critical features or requires extensive customization will ultimately cost more in the long run. Evaluate the implementation timeline to ensure it aligns with the carrier's product launch goals. According to recent data, successful implementations typically take 12 to 18 months, depending on the complexity of the existing infrastructure.
Key Takeaways
- Yield Pressure: Traditional fixed-income yields are insufficient, driving carriers to seek alternative assets for enhanced returns.
- Valuation Complexity: Accurate fair value measurement is critical for reserve adequacy and regulatory compliance.
- Liquidity Risk: Real-time visibility into liquidity profiles is essential to meet policyholder surrender obligations.
- Integration Needs: API-first architecture is required for seamless connectivity with core systems and general ledgers.
- Regulatory Scrutiny: Automated reporting and stress testing capabilities are non-negotiable for modern compliance.
- Vendor Expertise: Choose a partner with deep insurance industry knowledge, not just general asset management experience.
- Total Cost of Ownership: Evaluate long-term costs, including customization and maintenance, rather than just initial licensing fees.
Frequently Asked Questions
What are the primary risks associated with alternative assets for annuity carriers?
The primary risks include liquidity risk, valuation uncertainty, and credit risk. Unlike public markets, alternative assets lack a transparent pricing mechanism and may have long lock-up periods, making it difficult to sell assets quickly without incurring significant losses.
How does a modern platform improve liquidity management?
A modern platform provides real-time dashboards that aggregate liquidity data across all asset classes. It allows carriers to model redemption scenarios and predict cash flow needs, ensuring that sufficient liquid assets are available to meet policyholder demands.
Why is API-first architecture important for annuity carriers?
API-first architecture enables seamless integration with existing core systems, reducing the need for manual data entry and minimizing errors. It also allows carriers to adapt quickly to new regulatory requirements or business needs by connecting with best-of-breed tools.
What role does stress testing play in alternative asset management?
Stress testing helps carriers understand the potential impact of adverse market conditions on their alternative asset portfolios. It is crucial for determining reserve adequacy and ensuring that the carrier can withstand economic shocks without jeopardizing its financial stability.
How long does it typically take to implement a new alternative asset platform?
Implementation timelines vary based on complexity but typically range from 12 to 18 months. This includes data migration, system configuration, testing, and user training. Carriers should plan for this timeline when launching new products.
What are the key regulatory reporting requirements for alternative assets?
Carriers must report detailed information on asset classes, valuation methods, and liquidity profiles to regulators such as the NAIC. Automated reporting tools help ensure accuracy and timeliness, reducing the risk of compliance violations.
How can carriers ensure data integrity in alternative asset portfolios?
Carriers should implement robust data governance frameworks that include data validation, lineage tracking, and regular audits. The platform should provide tools to cleanse and normalize data from multiple sources to ensure consistency and accuracy.
Next Steps
Transitioning to alternative assets is a complex but necessary evolution for annuity carriers seeking to remain competitive. The right platform can provide the technology, expertise, and support needed to navigate this transition successfully. At Acturion Group, we specialize in helping insurance carriers optimize their actuarial and investment processes. Our team offers deep expertise in alternative asset modeling and regulatory compliance. Explore our actuarial consulting services to learn how we can support your strategic goals. Learn more about our firm and our commitment to excellence. Read our latest insights on industry trends. Contact us today to schedule a consultation. Download our whitepapers for deeper analysis.