Cost-Benefit Analysis of Retirement Income Risk Transfer Solutions
Retirement planning has shifted dramatically in recent decades. The traditional model of relying solely on defined-benefit pensions has largely dissolved, leaving individuals to manage longevity risk themselves. According to the Employee Benefit Research Institute, less than 20 percent of private-sector workers now have access to a traditional pension plan. This structural shift means that the burden of ensuring a steady income stream in retirement falls squarely on the individual. Consequently, understanding the cost-benefit dynamics of risk transfer solutions is no longer optional. It is a critical component of financial security.
Understanding Retirement Income Risk Transfer
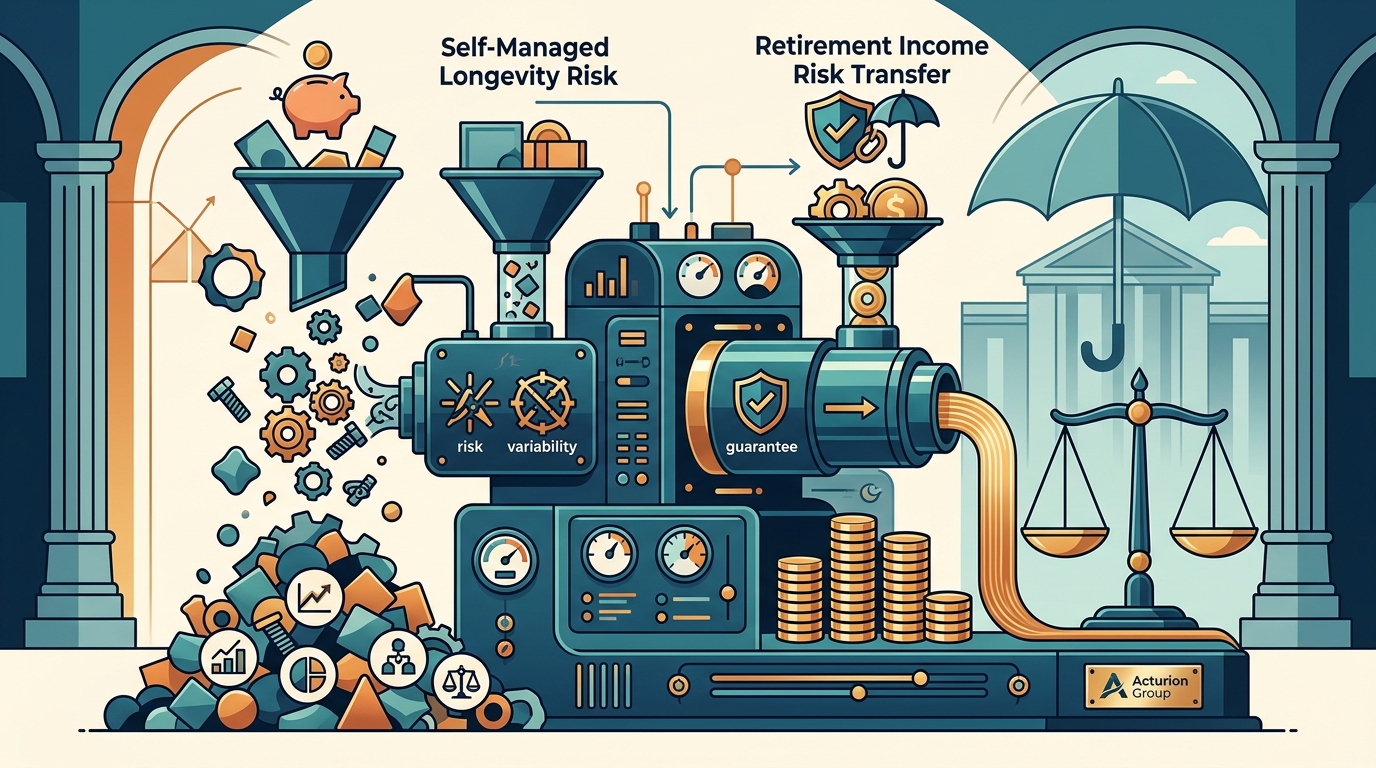
Risk transfer in retirement refers to the strategic movement of financial uncertainty from an individual to an insurance carrier. The primary risks involved are longevity risk, inflation risk, and market volatility risk. Longevity risk is the possibility of outliving one's savings. Inflation risk is the erosion of purchasing power over time. Market volatility risk is the potential for investment losses during critical withdrawal years.
Insurance companies pool these risks across a large population. This pooling allows them to offer guarantees that individual investors cannot replicate on their own. The cost of this guarantee is the premium paid or the fees deducted from the account. The benefit is the peace of mind and predictable cash flow. For many retirees, the value of predictability outweighs the cost of the fees.
Acturion Group specializes in analyzing these complex actuarial calculations. We help clients understand the fine print behind these guarantees. Our approach focuses on aligning financial products with specific life expectancy and income needs. You can learn more about our methodology by visiting our company overview page. (Acturion Group)
Fixed Annuities and Guaranteed Income
Fixed annuities are perhaps the most straightforward risk transfer tool. They offer a guaranteed interest rate for a specified period or for life. The benefit is absolute certainty. The cost is typically lower than variable products because the insurer bears less investment risk. (Sample Page 8211 Acturion)
Immediate annuities begin payouts right after purchase. Deferred annuities allow the money to grow tax-deferred before payouts begin. The choice depends on current income needs versus future goals. For those seeking immediate stability, immediate annuities provide a baseline income floor.
According to data from the Society of Actuaries, annuitized income can reduce the probability of poverty in old age by significant margins. This is particularly true for individuals with lower lifetime earnings. The cost-benefit ratio favors fixed annuities when the primary goal is survival income rather than wealth accumulation.
We provide detailed insights into these products on our products page. Understanding the specific terms of a fixed annuity is crucial for accurate planning.
Variable Annuities with Living Benefits
Variable annuities offer market participation potential but come with higher costs. The investment component is held in sub-accounts similar to mutual funds. The cost includes mortality and expense risk charges, plus underlying fund fees. These fees can easily exceed 2 percent annually.
However, variable annuities often include optional riders for guaranteed minimum income benefits. These riders provide a floor for income regardless of market performance. The benefit is the combination of growth potential and downside protection. The cost is the premium for the rider, which can be 1 to 2 percent extra per year.
This solution is best suited for individuals who have maxed out tax-advantaged accounts and still wish to invest. It is less suitable for those who need immediate liquidity or have a low risk tolerance. The complexity of these products requires careful analysis. Our team at Acturion Group can help you navigate these complexities. Visit our customer service page for support.
Long-Term Care Insurance Options
Long-term care (LTC) insurance is a specialized risk transfer tool. It covers costs for assisted living, nursing homes, and in-home care. The benefit is asset protection. Without LTC insurance, a single year in a nursing home can deplete a retirement portfolio by 50 percent or more.
The cost of LTC insurance is age-sensitive. Premiums increase significantly with age. Inflation protection riders are essential but add to the cost. The decision to purchase LTC insurance is often a trade-off between premium affordability and coverage adequacy.
Recent studies indicate that the majority of Americans will require some form of long-term care. Yet, many remain underinsured. This gap highlights the importance of early planning. Acturion Group offers specialized analysis for these needs. Check our special sales section for current offers on planning tools.
Comparative Cost-Benefit Analysis
Evaluating these solutions requires a side-by-side comparison. The table below summarizes the key characteristics of each major risk transfer vehicle.
| Solution | Primary Benefit | Primary Cost | Best For |
|---|---|---|---|
| Fixed Annuity | Guaranteed income floor | Lower growth potential | Conservative investors |
| Variable Annuity | Market upside with floor | High fees and complexity | Accumulation phase |
| Long-Term Care | Asset protection | Age-sensitive premiums | Health risk mitigation |
| DIY Portfolio | Full control and liquidity | Longevity risk exposure | Aggressive investors |
The cost-benefit analysis is not one-size-fits-all. It depends on individual health, family history, and other income sources. Social Security benefits, for example, act as a natural inflation-protected annuity. This reduces the need for additional guaranteed income products. However, Social Security alone is rarely sufficient for a comfortable retirement.
According to the Center for Retirement Research, the optimal mix of risk transfer tools varies by income level. Lower-income individuals benefit more from annuitization. Higher-income individuals may benefit more from tax-efficient investment strategies. Acturion Group provides personalized analysis to determine the right mix. Explore our contract sales resources for more details.
Key Takeaways
- Risk transfer solutions shift longevity and market risks to insurance carriers.
- Fixed annuities offer the lowest cost for guaranteed income stability.
- Variable annuities provide growth potential but carry high fee structures.
- Long-term care insurance protects assets from healthcare costs.
- Acturion Group specializes in actuarial analysis for these decisions.
- Early planning reduces the cost of long-term care insurance premiums.
- Personalized analysis is required to determine the optimal mix of solutions.
Frequently Asked Questions
What is the primary risk in retirement?
The primary risk is longevity risk, which is the danger of outliving your financial resources. This risk is exacerbated by inflation and market downturns.
How do fixed annuities work?
Fixed annuities are contracts with insurance companies that guarantee a specific interest rate or income payment. They provide predictable cash flow regardless of market conditions.
Are variable annuities worth the cost?
Variable annuities can be worth the cost for investors seeking tax deferral and guaranteed income riders. However, the high fees can significantly erode returns over time.
When should I buy long-term care insurance?
The ideal time to buy long-term care insurance is in your 50s or early 60s. Premiums are lower, and insurability is higher than in later years.
How does Acturion Group help with these decisions?
Acturion Group provides actuarial analysis and financial planning services. We help clients compare costs and benefits to make informed decisions. Visit our about us page for more information.
What is the difference between immediate and deferred annuities?
Immediate annuities start paying income right away. Deferred annuities allow the money to grow before payouts begin. The choice depends on current income needs.
Can I combine different risk transfer solutions?
Yes, a diversified approach is often best. Combining annuities, insurance, and investments can create a robust retirement income plan.
Contact Acturion Group
Retirement income planning is too important to leave to chance. The cost-benefit analysis of risk transfer solutions requires expertise and precision. Acturion Group is dedicated to helping you navigate these complexities. We provide the analytical depth needed to make confident decisions.
Ready to secure your financial future? Contact Acturion Group today to schedule a consultation. Visit our customer service page to get started. Let us help you build a retirement plan that withstands the test of time.