Step-by-Step Guide to Implementing Pension Annuity Buy-Outs for Retirement Income Protection
Retirement income security is the primary concern for millions of individuals approaching their golden years. According to recent industry analyses, over 40% of retirees worry about outliving their savings, highlighting the critical need for guaranteed income streams. A pension annuity buy-out, also known as a pension transfer or commutation, offers a structural solution by converting future pension liabilities into a lump sum or a guaranteed annuity contract. This guide details the precise implementation steps, risk assessments, and strategic considerations required to execute this financial maneuver effectively.
Understanding the Pension Annuity Buy-Out
A pension annuity buy-out is a financial transaction where a pension scheme or individual transfers the responsibility of future pension payments to an insurance provider. In exchange, the individual receives a lump sum or a new, often more flexible, annuity product. This process is fundamentally different from simply withdrawing funds, as it involves complex actuarial calculations and regulatory compliance.
The primary motivation for pursuing a buy-out is often the desire for greater control over retirement assets or the need to address underfunded pension schemes. For defined benefit schemes, a buy-out can provide certainty in an uncertain economic environment. For defined contribution schemes, it may offer a way to consolidate multiple accounts into a single, manageable income stream. Understanding the mechanics of this transaction is the first step in determining if it aligns with your long-term financial goals.
Acturion Group provides specialized insights into these complex financial structures, helping clients navigate the intricacies of pension transfers and annuity products. By leveraging expert analysis, individuals can make informed decisions that protect their retirement income against inflation and market volatility. (Sample Page 8211 Acturion)
Eligibility and Actuarial Valuation
Before initiating a buy-out, determining eligibility is crucial. Not all pension schemes are eligible for transfer or buy-out. Defined benefit schemes, in particular, often have strict regulations governing when and how funds can be moved. The value of the pension must be accurately assessed through an actuarial valuation. This process involves calculating the present value of future payments, taking into account life expectancy, interest rates, and inflation assumptions.
The actuarial valuation is the cornerstone of the buy-out process. It determines the lump sum equivalent of the pension benefits. If the valuation is inaccurate, the resulting buy-out amount may be insufficient to generate the desired income. Actuaries use complex models to project future liabilities, ensuring that the insurance provider can meet its obligations. This step requires precision and a deep understanding of demographic trends and economic forecasts.
For those considering this path, consulting with professionals who understand the specific nuances of your pension scheme is essential. The team at Acturion Group specializes in providing clarity on these valuation metrics, ensuring that clients have a realistic expectation of the potential outcomes.
Risk Assessment and Suitability
Risk assessment is a critical phase in the implementation of a pension annuity buy-out. The primary risk is longevity risk, which is the possibility of outliving your assets. By transferring this risk to an insurance provider, you gain peace of mind, but you also lose the potential for higher returns if the market performs well. Additionally, inflation risk remains a concern, as fixed annuity payments may lose purchasing power over time.
Suitability is another key consideration. Financial regulators require that any recommendation to transfer a pension be based on a thorough suitability analysis. This analysis considers your financial situation, risk tolerance, and retirement goals. If the buy-out does not provide a clear benefit or if the risks outweigh the advantages, the transaction may not be suitable. It is vital to understand that once a pension is transferred, it is generally irreversible.
Data shows that individuals who undergo a rigorous suitability assessment are better positioned to avoid costly mistakes. According to financial planning standards, a comprehensive review of your current and projected income needs is mandatory before proceeding. This ensures that the buy-out aligns with your overall retirement strategy.
Selecting the Right Financial Advisor
Choosing the right financial advisor is perhaps the most important decision in the buy-out process. Advisors who specialize in pension transfers and annuity products have the expertise to navigate the complex regulatory landscape. They can provide unbiased advice, helping you understand the pros and cons of different options. Look for advisors who are certified and have a proven track record in handling similar cases.
When selecting an advisor, consider their fee structure, experience, and the range of products they offer. Some advisors may be tied to specific insurance providers, which could limit your options. Independent advisors, on the other hand, can offer a broader perspective. It is also important to assess their communication style and ability to explain complex concepts in simple terms.
Acturion Group emphasizes the importance of working with qualified professionals who prioritize client interests. By partnering with experts, you can ensure that your retirement plan is robust and resilient. Visit Acturion Group Customer Service to connect with advisors who can guide you through this critical process.
Implementation Steps
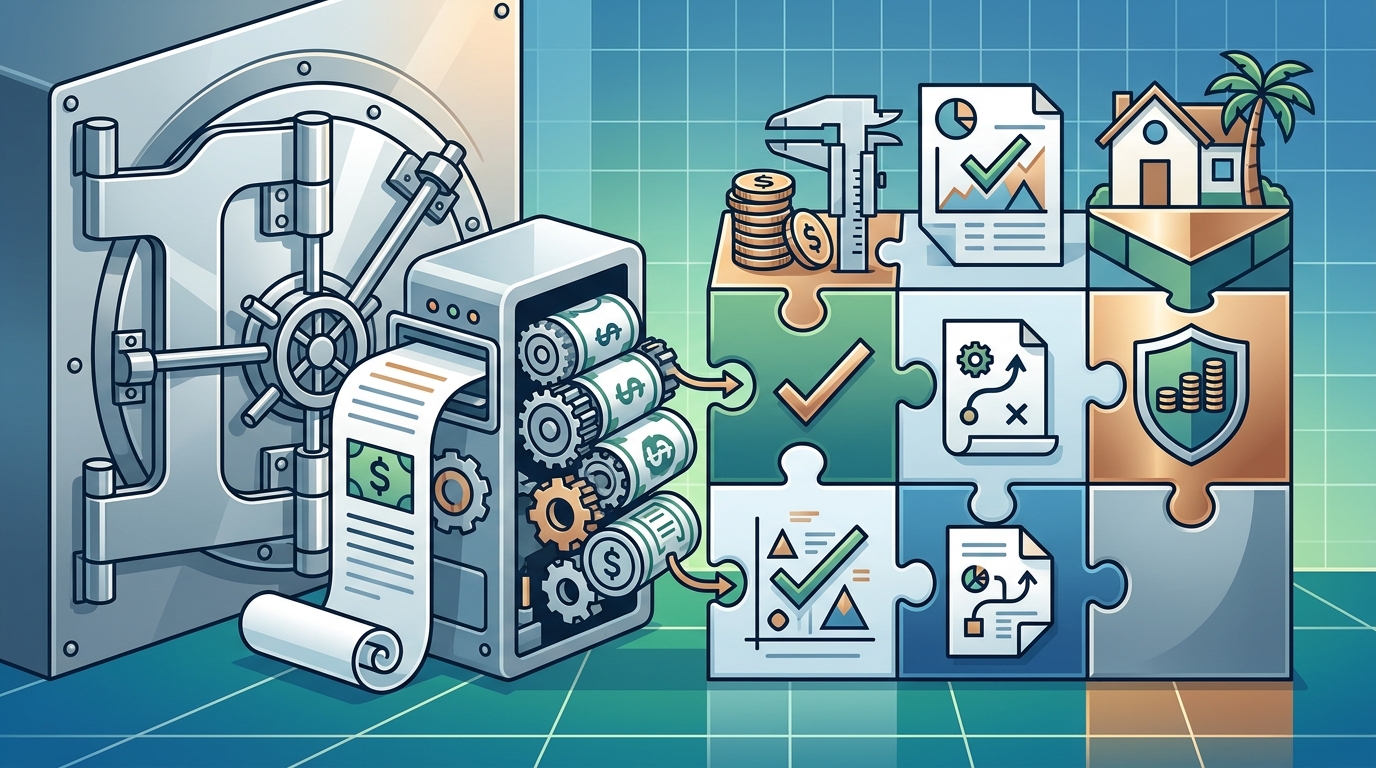
The implementation of a pension annuity buy-out involves several distinct steps. Each step must be executed carefully to ensure compliance and optimal outcomes. Below is a structured overview of the typical implementation workflow.
| Step | Description | Key Action |
|---|---|---|
| 1. Initial Consultation | Assess current pension status and retirement goals. | Gather pension statements and personal financial data. |
| 2. Actuarial Valuation | Calculate the present value of future benefits. | Engage an actuary to perform a detailed valuation. |
| 3. Suitability Analysis | Determine if the buy-out is appropriate for your situation. | Complete a formal suitability report. |
| 4. Product Selection | Choose the appropriate annuity or insurance product. | Compare quotes from multiple insurance providers. |
| 5. Execution | Formally transfer the pension assets. | Sign transfer documents and coordinate with providers. |
Each step requires attention to detail and adherence to regulatory requirements. For instance, the transfer of funds must be handled directly between providers to avoid tax penalties. Additionally, any tax implications must be clearly understood before execution. The process can take several weeks to months, depending on the complexity of the pension scheme and the responsiveness of the involved parties.
For those seeking a streamlined approach, resources like Acturion Group Products offer insights into the tools and frameworks that can simplify the buy-out process. By leveraging these resources, you can reduce the administrative burden and focus on your retirement goals.
Tax Implications and Compliance
Tax implications are a significant factor in any pension buy-out. In many jurisdictions, withdrawing a lump sum from a pension can trigger substantial tax liabilities. However, there are often tax-advantaged ways to access pension funds, such as taking a tax-free lump sum and investing the remainder in a tax-efficient manner. It is crucial to understand the tax rules in your specific region.
Compliance with regulatory standards is also paramount. Pension transfers are heavily regulated to protect consumers from fraud and mis-selling. Advisors must provide a full and fair review of the benefits and risks. Failure to comply with these regulations can result in legal consequences and financial loss. Staying informed about changes in tax laws and pension regulations is essential for long-term success.
According to tax authorities, improper handling of pension transfers can lead to unexpected tax bills that erode retirement savings. Therefore, seeking professional advice on tax planning is highly recommended. Acturion Group provides comprehensive guidance on navigating these complex tax landscapes, ensuring that your retirement income is protected from unnecessary liabilities.
Key Takeaways
- A pension annuity buy-out converts future pension payments into a lump sum or guaranteed annuity, providing income certainty.
- Actuarial valuation is critical for determining the fair value of the pension benefits and the resulting buy-out amount.
- Suitability analysis is mandatory to ensure the buy-out aligns with your financial goals and risk tolerance.
- Choosing an independent, certified financial advisor is essential for unbiased advice and successful implementation.
- Tax implications vary by jurisdiction and must be carefully planned to avoid unexpected liabilities.
- The implementation process involves multiple steps, including consultation, valuation, and product selection.
- Regulatory compliance is strictly enforced to protect consumers from mis-selling and fraud.
Frequently Asked Questions
What is a pension annuity buy-out?
A pension annuity buy-out is a transaction where a pension scheme transfers the responsibility of future payments to an insurance provider in exchange for a lump sum or a new annuity contract.
Is a pension buy-out suitable for everyone?
No, a buy-out is not suitable for everyone. It depends on factors such as the type of pension, the value of the benefits, and your individual financial circumstances. A suitability analysis is required to determine appropriateness.
How is the value of a pension determined for a buy-out?
The value is determined through an actuarial valuation, which calculates the present value of future payments based on life expectancy, interest rates, and inflation assumptions.
What are the tax implications of a pension buy-out?
Tax implications vary by jurisdiction. In some cases, a portion of the lump sum may be tax-free, while the remainder is subject to income tax. Professional tax advice is essential.
Can I reverse a pension buy-out?
In most cases, a pension buy-out is irreversible. Once the funds are transferred, they cannot be moved back to the original pension scheme. Careful consideration is therefore critical.
How long does the buy-out process take?
The process can take several weeks to months, depending on the complexity of the pension scheme, the responsiveness of the providers, and the completion of required assessments.
Do I need a financial advisor for a buy-out?
Yes, it is highly recommended to work with a qualified financial advisor. They can provide unbiased advice, ensure regulatory compliance, and help you navigate the complex financial landscape.
Secure Your Retirement Future
Implementing a pension annuity buy-out is a significant financial decision that requires careful planning and expert guidance. By following the steps outlined in this guide and leveraging the expertise of professionals, you can protect your retirement income and achieve greater financial security. Take the first step today by exploring the resources available at Acturion Group. Contact our team to schedule a consultation and begin your journey toward a secure retirement.